


The right card issuing platform should support your target markets, card types and operating model. Before comparing providers, define where your cardholders live, whether you need debit, prepaid or credit cards, and which responsibilities you expect your partner to handle.
This guide compares nine card issuing and processing providers: Marqeta, Paymentology, Fiserv, Wallester, SoFi Tech Solutions (formerly Galileo), Stripe Issuing, Solaris, Lithic and Thredd. The comparison highlights their roles, capabilities and programme requirements to help you build a shortlist that fits your product.
SDK.finance plays a separate role as the technology infrastructure around a card programme. Our Transaction Platform connects customer accounts and application-side card workflows with Marqeta through an integration, while regulated card issuance remains with the relevant licensed issuer. Below, we explain how this infrastructure fits alongside issuing and processing providers.
Card issuing platforms compared at a glance
Card issuing providers play different roles, from processing transactions to supporting broader card programmes. The table below compares nine providers by programme scope, suitable use cases and key dependencies. It also includes SDK.finance as the technology infrastructure supporting a card programme, with a separate role from issuing and processing providers.
| Provider | Role | Programme scope | Suitable use case | Key dependency |
|---|---|---|---|---|
| Marqeta | Issuing and processing platform | Debit, prepaid and credit | Programmable card products | Issuing-bank and programme approval |
| Paymentology | Issuer processor | Debit, prepaid and credit | Multi-market processing | Market-specific sponsor arrangement |
| Fiserv | Issuer processing | Credit, debit and prepaid | Banks and portfolio modernisation | Regional platform and service scope |
| Wallester | Visa issuing and processing | Debit, prepaid and credit | Branded EEA and UK programmes | Eligibility and agreed issuing model |
| SoFi Tech Solutions | Card issuing and processing technology | Credit, debit, prepaid and virtual | Cards within broader financial products | Bank partner and market approval |
| Stripe Issuing | Bank-partner issuing platform | Commercial programmes; physical and virtual | Embedded commercial cards | Supported country and bank approval |
| Solaris | Bank-led embedded finance | Debit, prepaid and credit | Cards with banking services | Product and country eligibility |
| Lithic | Issuing and processing platform | Credit, debit and prepaid | API-driven card programmes | Processing or managed programme model |
| Thredd | Issuer processor | Debit, prepaid and credit | Card processing across markets | Issuing partner and contracted scope |
| SDK.finance | Core technology infrastructure for card issuing programmes | Accounts, wallets, balances and card workflows across issuing-provider integrations | Building a payment product with integrated card features | Issuing-provider agreement |
Card issuing platforms and providers compared
Card issuing platforms support different parts of a card programme, from the technology that processes transactions to the services that connect businesses with issuing banks. The right fit depends on the cards you want to offer, your target markets and the infrastructure you already have. The following nine providers illustrate these differences, with an overview of their capabilities, programme scope and business applications.
Marqeta
Headquarters: Oakland, California, US.
Founded in: 2010.
Marqeta is an API-based card issuing and processing platform for debit, prepaid and credit programmes. It suits businesses that want to customise how cards work for customers, employees or suppliers, with bank and network relationships available as part of the agreed programme.
Key strengths: Programmable card products, dynamic spending controls and just-in-time funding.
Supported card programmes: Debit, prepaid and credit.
Main features
- APIs for creating and managing card products.
- Dynamic spending controls and just-in-time funding.
- Virtual cards, digital-wallet integration and tokenisation.
Paymentology
Headquarters: London, UK.
Founded in: 2014 (business origins); UK company incorporated in 2015.
Paymentology provides issuer-processing technology for banks and FinTechs operating debit, prepaid, credit and virtual-card programmes. Its processing, data and risk tools support businesses expanding across markets, with issuing arrangements provided through the relevant bank or BIN-sponsor relationship.
Key strengths: Processing across multiple markets, transaction data and digital-wallet capabilities.
Supported card programmes: Debit, prepaid, credit and virtual-card programmes.
Main features
- Card processing with transaction decisioning and operational data tools.
- Tokenisation and provisioning cards into supported digital wallets.
- Fraud controls and 3D Secure authentication.
Fiserv
Headquarters: Milwaukee, Wisconsin, US.
Founded in: 1984.
Fiserv offers card processing and servicing technology for banks and established issuers. Its portfolio supports credit, debit, prepaid and commercial-card programmes. Products such as FirstVision and VisionPLUS form part of its EMEA offering, with the platform and services selected for each market.
Key strengths: Issuer processing, card servicing and integration with established banking systems.
Supported card programmes: Credit, debit, prepaid and commercial cards; scope varies by regional product.
Main features
- Card management and customer-servicing tools.
- Data services, digital capabilities and financial-crime prevention options.
- APIs for connecting card processing with existing banking operations.
Wallester
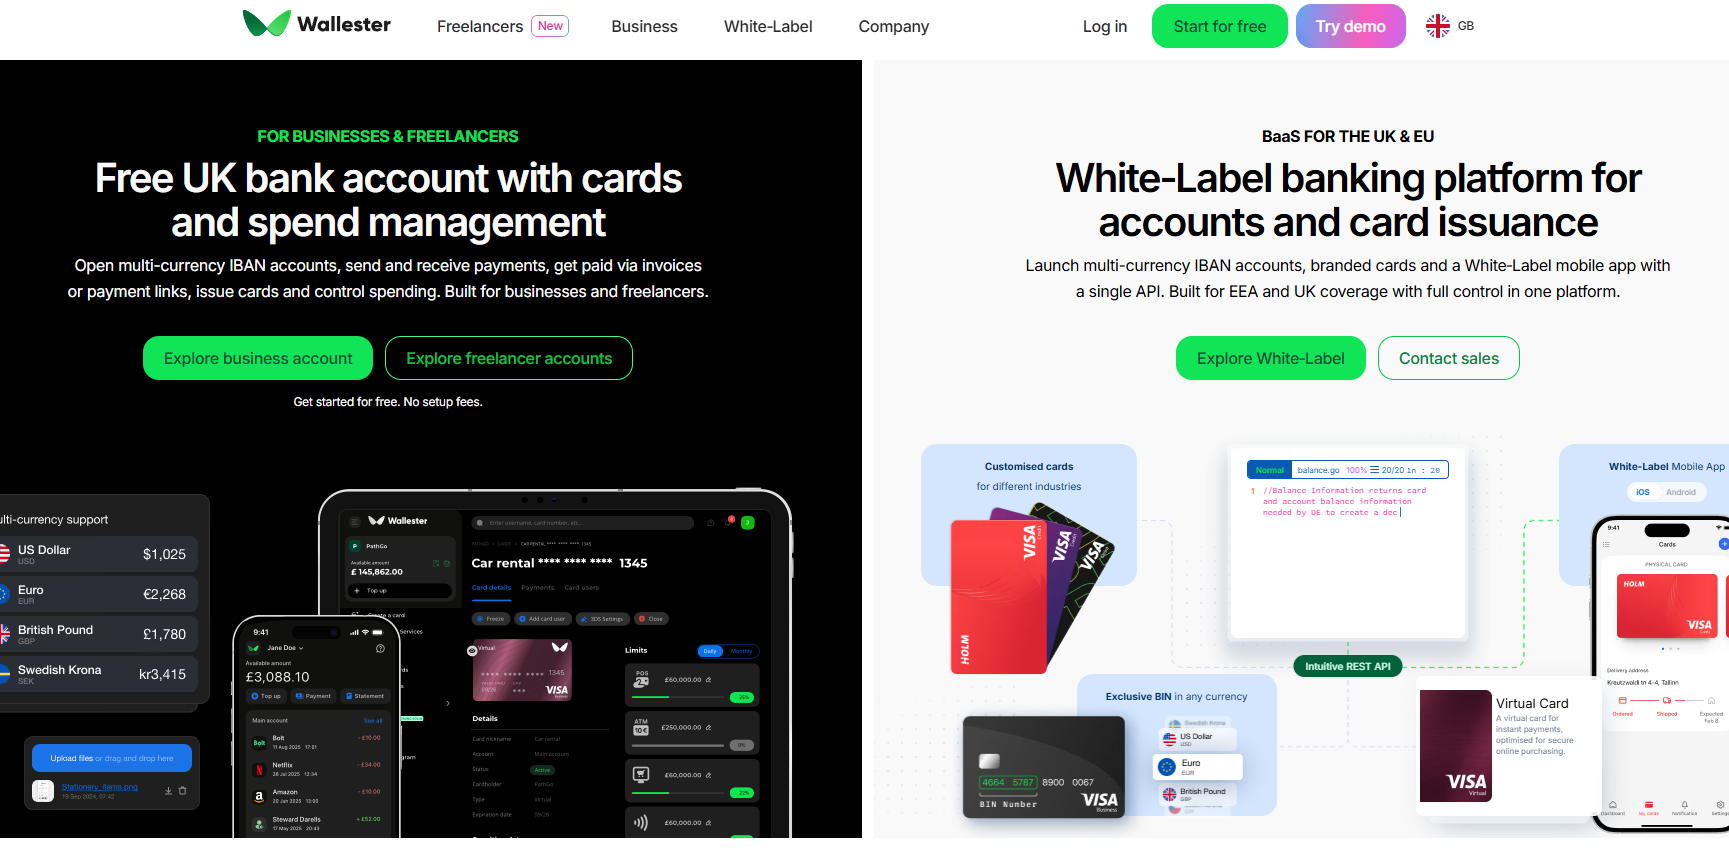
Headquarters: Tallinn, Estonia.
Founded in: 2016.
Wallester White-Label combines branded Visa card issuing, processing and programme support for businesses in the EEA and UK. Its offering covers debit, prepaid and credit programmes, with physical and virtual cards. Product availability and services depend on the agreed programme.
Key strengths: Branded Visa programmes, physical and virtual cards, and BIN sponsorship.
Supported card programmes: Debit, prepaid and credit, with physical and virtual cards.
Main features
- Branded card programmes with configurable rules and spending controls.
- Physical and virtual cards with Apple Pay and Google Pay support.
- BIN sponsorship and operational support.
SoFi Tech Solutions (formerly Galileo)
Headquarters: Salt Lake City, Utah, US (Galileo business).
Founded in: 2000 as Galileo; transition to the SoFi Tech Solutions brand announced in 2026.
SoFi Tech Solutions, formerly Galileo, provides card issuing and processing technology for FinTechs and financial institutions. Its offering covers credit, debit, prepaid and virtual cards through APIs, alongside account, payment and risk capabilities for broader financial products.
Key strengths: Card issuing and processing APIs alongside account, payment and risk capabilities.
Supported card programmes: Credit, debit, prepaid and virtual cards.
Main features
- APIs for card issuing and transaction processing.
- Programme-management and operational service options.
- Account, payment and risk capabilities within the broader product portfolio.
Stripe Issuing
Headquarters: San Francisco, US, and Dublin, Ireland (Stripe).
Founded in: 2010 (Stripe, the company behind Stripe Issuing).
Stripe Issuing helps platforms create and manage commercial card programmes using APIs and dashboards. It supports physical and virtual cards for business spending and embedded financial products. Cards are issued by Stripe’s bank partners, with availability depending on the country and programme.
Key strengths: Commercial card programmes, real-time spending controls and API-based management.
Supported card programmes: Commercial physical and virtual cards, including eligible charge-card programmes.
Main features
- APIs and dashboards for card creation and management.
- Spending controls and real-time authorisation decisions.
- Commercial spend and charge-card programmes, subject to eligibility.
Solaris
Headquarters: Berlin, Germany.
Founded in: 2016.
Solaris combines branded card products with a bank-led embedded-finance offering. Businesses can build debit, prepaid or credit card programmes alongside banking services, with the product and country scope determined by the partnership.
Key strengths: Branded card products combined with bank-led embedded-finance services.
Supported card programmes: Debit, prepaid and credit; availability depends on the partnership.
Main features
- Card creation and lifecycle management.
- Spending controls and 3D Secure authentication.
- Tokenisation and provisioning into supported digital wallets.
Lithic
Headquarters: New York, US.
Founded in: 2014 as Privacy.com.
Lithic provides API-based infrastructure for credit, debit and prepaid card programmes serving individuals and businesses. Companies can use its processing technology with their own bank relationship or choose programme-management services, depending on how much operational responsibility they want to retain.
Key strengths: Developer-focused APIs, authorisation controls and a choice of processing service models.
Supported card programmes: Credit, debit and prepaid for individuals and businesses.
Main features
- Card issuance and mobile or web provisioning.
- Authorisation decisioning and configurable risk controls.
- Ledger and settlement interfaces for programme money movement.
Thredd
Headquarters: London, UK.
Founded in: 2007 as Global Processing Services.
Thredd provides issuer processing for debit, prepaid and credit programmes, including physical, virtual and tokenised cards. It supports programme teams operating across markets and offers introductions through its BIN-sponsor network, with issuing services subject to the selected partner arrangement.
Key strengths: Issuer processing across card types, digital-wallet support and operational reporting.
Supported card programmes: Debit, prepaid and credit, with physical, virtual and tokenised cards.
Main features
- Card controls and digital-wallet support.
- Risk, fraud and dispute-management tools.
- Account, balance and transaction records with reporting capabilities.
SDK.finance: the core technology infrastructure behind your card issuing programme
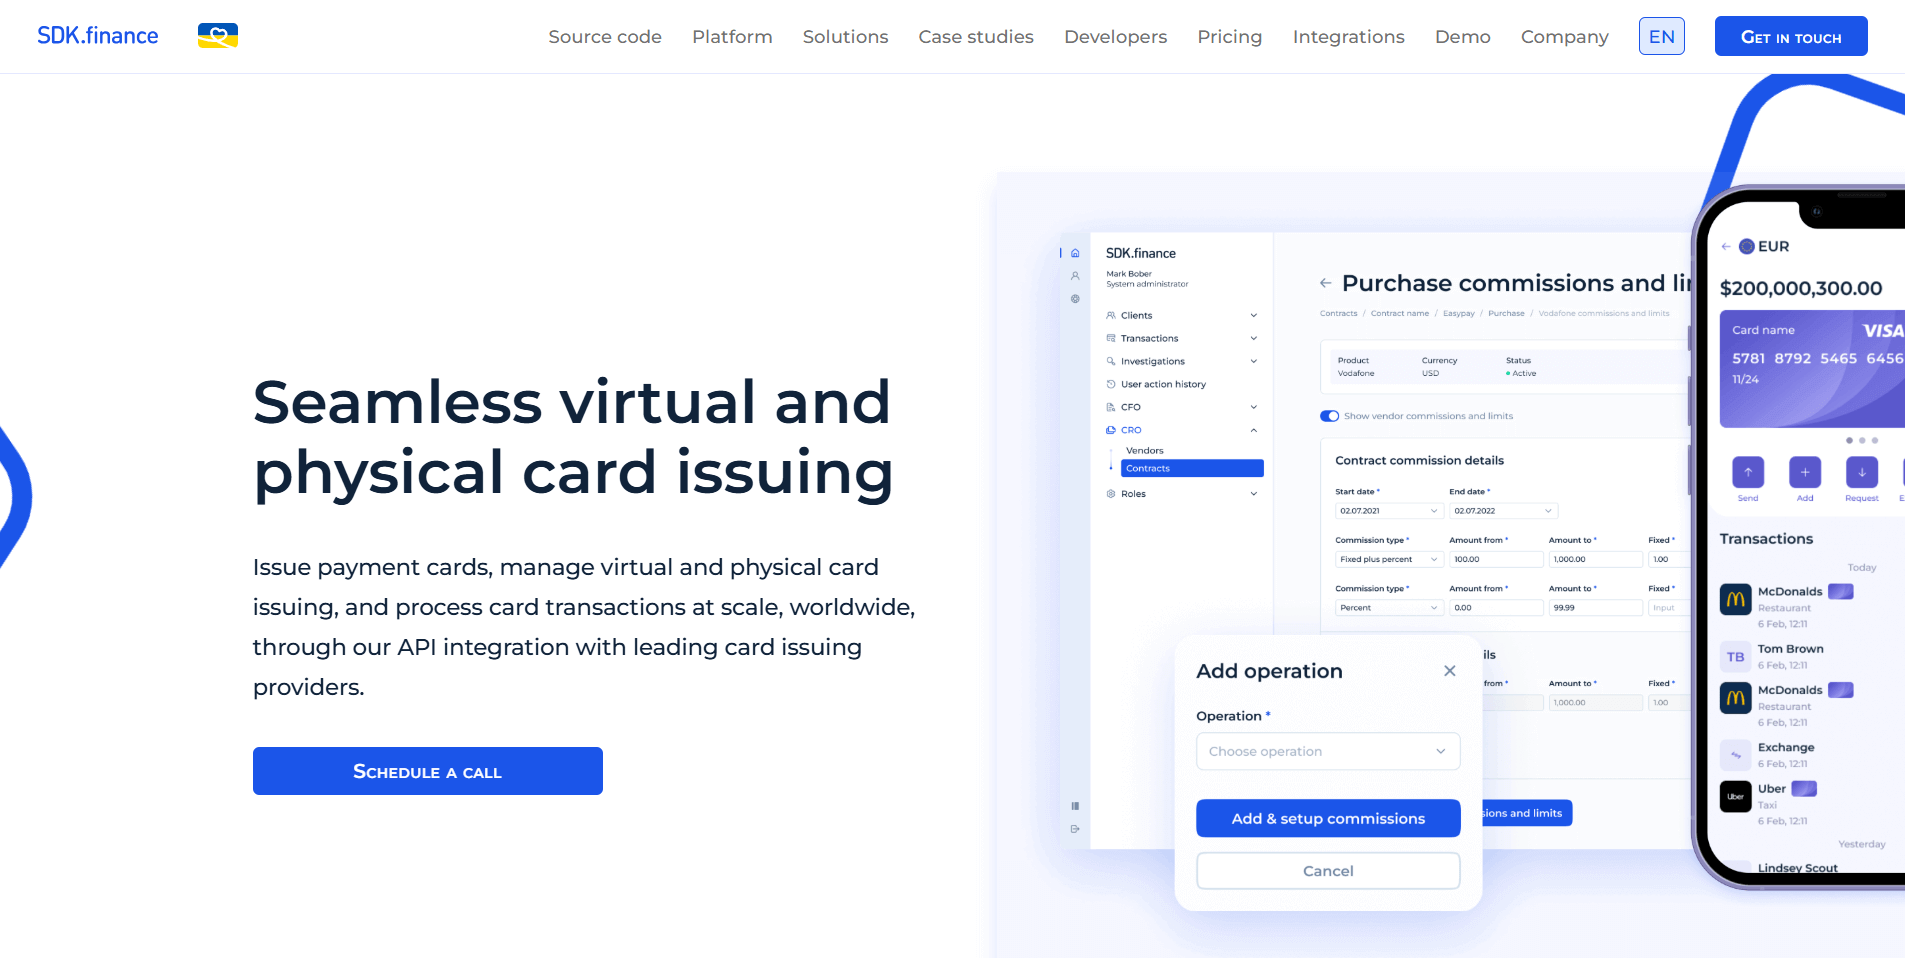
A card issuing programme needs a software core to manage customer accounts, funds, transactions and the workflows connecting your application to the issuing provider. SDK.finance supplies this foundation, bringing card functionality into a complete payment product.
Our Transaction Platform combines accounts, multi-currency wallets, balance management and payment operations with implemented card issuance workflows. Your team can build on this infrastructure to launch branded cards within a digital wallet or payment application and expand the product over time.
Issue branded cards through your chosen card issuing provider
SDK.finance connects the customer experience, financial accounts and operational processes behind your card programme:
- Accounts, wallets and balances: manage customer funds and link issued cards to accounts within your payment product.
- Card issuance workflows: handle physical and virtual card requests, connect customer profiles with provider-side cardholder records and link issued cards to the relevant accounts.
- Fees, limits and approvals: configure issuance fees and limits, apply customer contract rules and route requests for approval when required.
- Card lifecycle management: make card details, activation and blocking available through the issuing-provider integration.
- Web, mobile and back-office connectivity: use 650+ APIs to connect customer-facing applications with platform workflows, supported by back-office tools for customer and transaction management.
- Payment functionality beyond cards: build transfers, top-ups, withdrawals and currency exchange into the same product, using the Transaction Platform’s existing capabilities.
Ready-made integrations and flexibility to choose your provider
SDK.finance offers ready-made integrations, including Marqeta, and supports connecting other card issuing providers through additional integration work. This lets you select a partner that fits your target markets, card products and commercial model.
With the Marqeta integration, the foundational issuance flow is already implemented: the customer requests a card, SDK.finance handles the application-side workflow, sends the request to the provider and links the returned card record to the customer’s account.
SDK.finance provides the software core; your issuing partner provides access to regulated card issuance. Launch preparation centres on your provider agreement, connectivity and programme configuration, with additional development for provider-specific requirements.
This makes SDK.finance a foundation for the entire card-enabled payment product, from the accounts holding customer funds to the application and operational workflows that support everyday use.
Credit card issuing platforms: credit, debit and prepaid compared
A virtual card is a format, not a funding model: it can be debit, prepaid or credit. Your funding model affects balance management, credit risk and operational responsibilities.
| Programme | Questions to resolve |
|---|---|
| Debit or prepaid | How are funds loaded or linked to accounts? Who maintains balances, limits and funding restrictions? |
| Credit | Who extends credit, assesses applicants, sets limits, manages billing and collections, and bears credit risk? |
| Virtual or physical | Which formats, delivery processes, controls and digital-wallet options are available for the chosen programme? |
A credit card issuing platform needs to support more than transaction processing. For a FinTech credit card programme, the operating model must also cover lending, credit limits, billing and collections. When comparing credit card providers, distinguish the company supplying the credit card platform from the institution providing the credit. The same distinction matters for FinTech credit card companies building their own branded products.
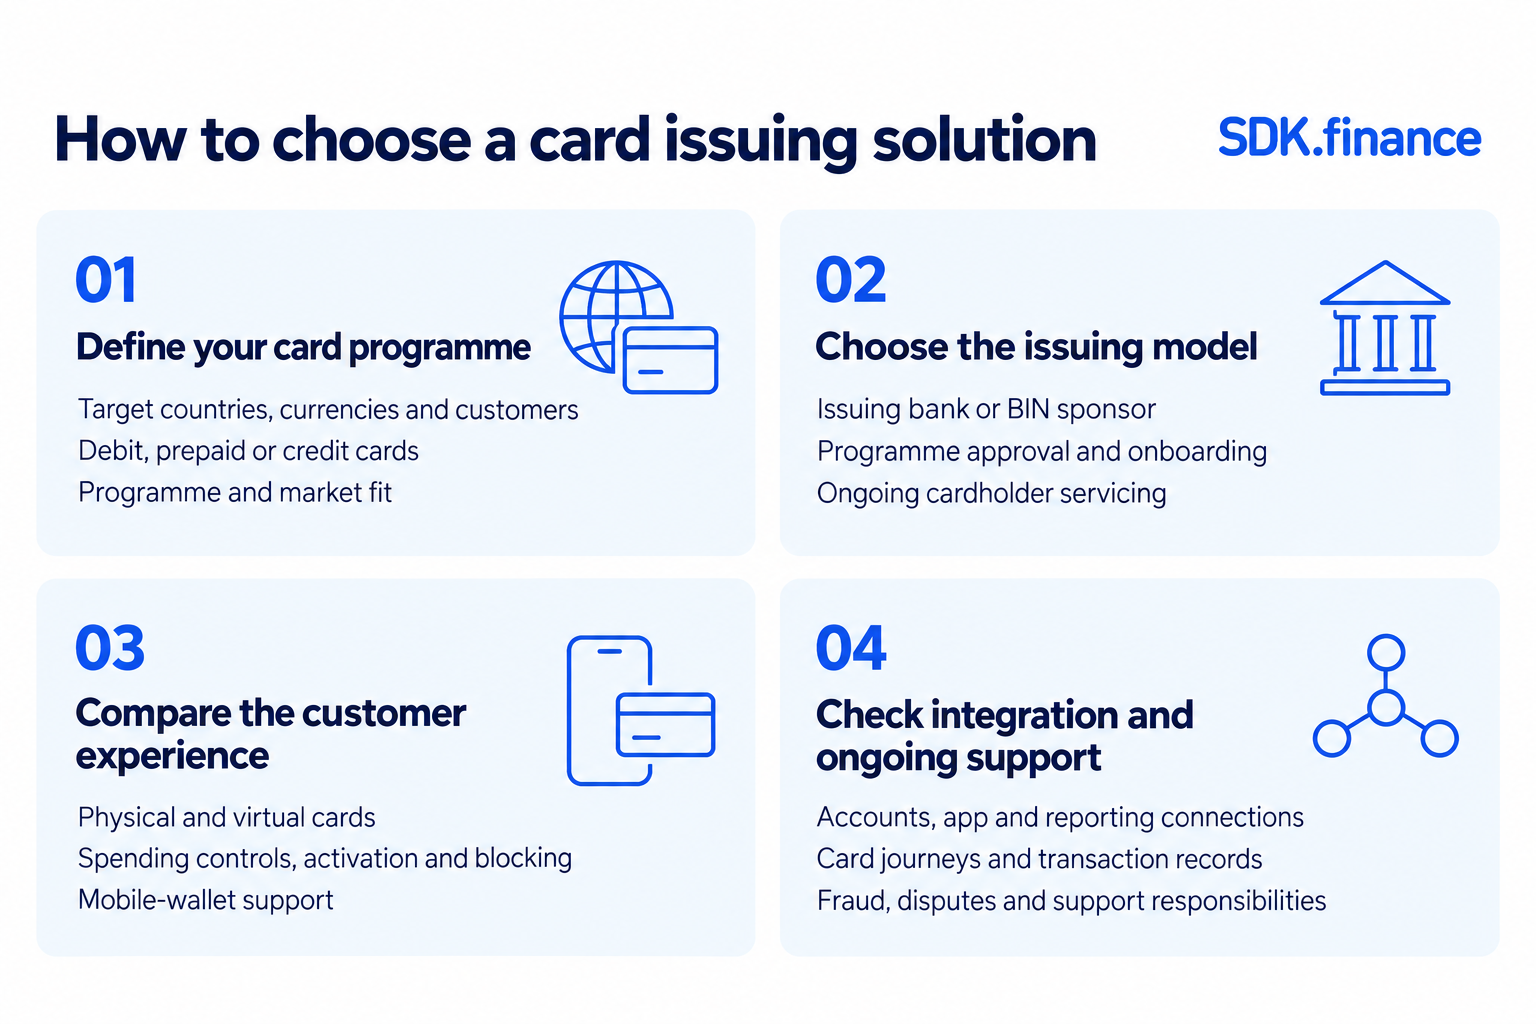
How to choose a card issuing solution
Define your card programme
Start with your target countries, currencies and customers. Decide whether you need debit, prepaid or credit cards, then shortlist solutions that support your programme and market.
Three things get conflated here, so keep them separate:
- Country availability – where the provider can legally issue, under its own or a partner’s licence.
- International usage – once issued, a Visa/Mastercard card generally works wherever the scheme is accepted, regardless of where the programme sits.
- Multi-currency support – whether cardholder accounts hold and settle in more than one currency, and how FX conversion is priced.
A multi-currency ledger behind the programme keeps balances and FX postings auditable per currency once more than one settlement currency is involved.
Choose the issuing model
Check whether the provider includes an issuing-bank or BIN-sponsor relationship, or expects you to arrange one. Agree who handles programme approval, onboarding and servicing.
Compare the customer experience
Match the platform to what your customers need: physical or virtual cards, spending controls, activation and blocking, mobile-wallet support. Prioritise what your first release actually needs.
Check integration and ongoing support
Review how the platform connects to your accounts, app and reporting tools. Test the main card journeys, then agree who owns fraud, disputes and support.
Choosing a card issuing platform for startups and marketplaces
Startups and marketplaces shop a different list than an established bank. Compare on:
- Costs and commercial terms – launch/setup fees, recurring platform payments, minimum volume commitments, and per-card or per-transaction costs.
- Issuing partner / BIN sponsorship – does the platform bring its own BIN-sponsor relationship, or do you arrange one?
- Sandbox access – can a small team test card creation and webhooks before signing?
- APIs and webhooks – event coverage for card states, authorisations, disputes – key for marketplaces reconciling many sellers/users.
- Spend management – configurable limits and just-in-time funding per user or seller.
- Security and operational responsibilities – which functions the provider takes on (fraud monitoring, dispute handling, KYC/compliance checks) and which stay with your own team.
Benefits of card issuing platforms
Card issuing platforms can help FinTech businesses build and operate card products by combining reusable technology with the services needed for their programme.
According to the European Central Bank, card payments represented 57% of the number of non-cash payments in the euro area in the second half of 2025. This shows the scale of card use in that market.
- Less development from scratch: existing card-creation and management APIs give teams a foundation for adding cards to an app.
- More control over spending: configurable limits and authorisation rules help businesses tailor card use to customers, employees or suppliers.
- A connected customer experience: physical cards, virtual cards and supported digital wallets give customers different ways to pay within the same programme.
- Clearer operational visibility: transaction data and reporting tools help teams track card activity and reconcile records.
The benefits depend on the chosen platform, integration and issuing arrangement. For the steps from planning to delivery, read how to launch a card programme.


