For a business planning to launch a digital wallet, the first decision is what the product will let customers do and which systems will support it. Banks, FinTechs, online stores, and telecoms use wallets to connect payments, balances, and services within their own products. Building one means designing the financial workflows and operational controls behind the customer experience.
This article explains what a digital wallet is, how its payment flows work, and what businesses need to consider when choosing a wallet model, architecture, and integrations. We’ll also look at SDK.finance, a FinTech software provider that offers a core on which businesses can build their digital wallets.
Ready backend, APIs, and integrations
Talk to Our TeamWhat is a digital wallet?
A digital wallet (or ewallet) is a software application or online service that lets users make electronic payments using stored payment credentials or a digital balance. Depending on the product, it may also hold loyalty cards, tickets, identification details, or transaction history.
Digital wallets can store:
- Credit and debit card information
- Bank account data
- Loyalty points and coupons
- Tickets or identification
- Cryptocurrency private keys, in wallets designed for digital assets
When a customer makes a payment, the wallet helps authenticate the instruction and sends it to the relevant payment system. A quick confirmation does not necessarily mean that funds have already settled between financial institutions.
Designing wallet onboarding and activation
Define the onboarding journey for your target customers: registration, account authentication, and any identity checks required for the service. Your team needs to connect these steps to the backend so that account status determines which wallet functions a customer can access.
Adding a card does not transfer money into the wallet, so the product must distinguish card linking from funding a balance.
How does a digital wallet work?
For a business building an ewallet, the payment flow determines which systems must exchange data, verify instructions, and record the result. The two common flows below show how a linked-card payment differs from spending a wallet balance.
Linked-card payment processing
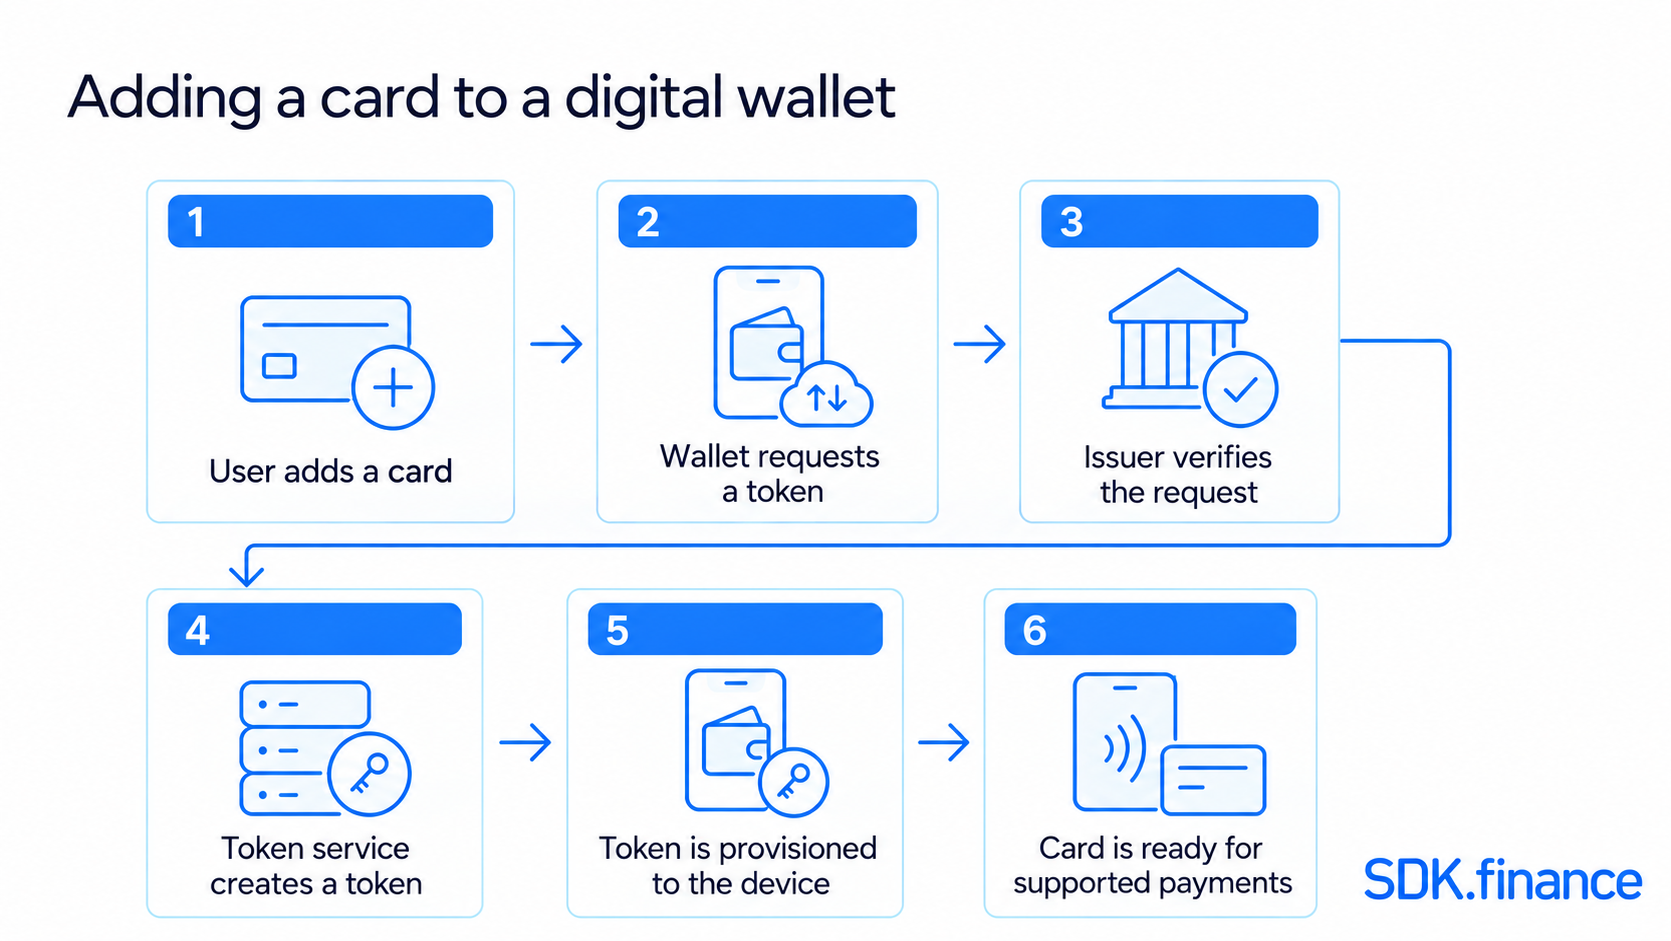
- Card provisioning. The wallet integrates with the issuer and, where applicable, a token service to verify card eligibility and provision payment credentials before the first payment.
- Payment authentication. The checkout integration captures the payment request, while the device or provider applies the required customer authentication.
- Authorisation routing. The request passes through the merchant’s payment infrastructure to the card issuer, which checks it and returns an approval or decline.
- Result handling. The integration returns the authorisation result to the checkout. Clearing and settlement follow the rules and timing of the payment network.
For example, Apple Pay uses a device-specific account number and a transaction-specific security code for supported card payments, rather than sending the actual card number to the merchant. In-store payments use NFC; online and in-app payments use the checkout integration.
Wallet-balance payment processing
- Funding confirmation. The backend records a top-up from a supported bank transfer, card payment, or cash-in service and updates available funds according to the confirmed transaction status.
- Payment instruction. The customer interface sends the recipient or merchant identifier and amount to the transaction-processing backend.
- Transaction checks. The wallet checks the available balance, applicable fees, limits, and authentication requirements before processing the instruction.
- Ledger and status updates. Once processed, the system records the transaction and updates the relevant balances. It makes the transaction status available to the customer interface and operations team.
An internal transfer can update two wallets within the same system. A payment to an external bank or provider also depends on that provider’s processing and payment rails. Design the interface and support workflow to distinguish pending, completed, and declined payments, so customers and operations teams can understand the result before initiating another payment.
Paying in-store, online, and with QR codes
Supporting in-store NFC payments requires compatible devices, terminals, and the relevant wallet and card integrations. Online and in-app payments require a checkout integration that passes payment details and returns the result to the customer.
With a QR payment, the customer scans the merchant’s code or presents a code for the merchant to scan, depending on the service. The interface should display the recipient and amount for confirmation. NFC and QR describe how payment details are exchanged; they do not determine whether the money comes from a card or a wallet balance.
The backend and APIs
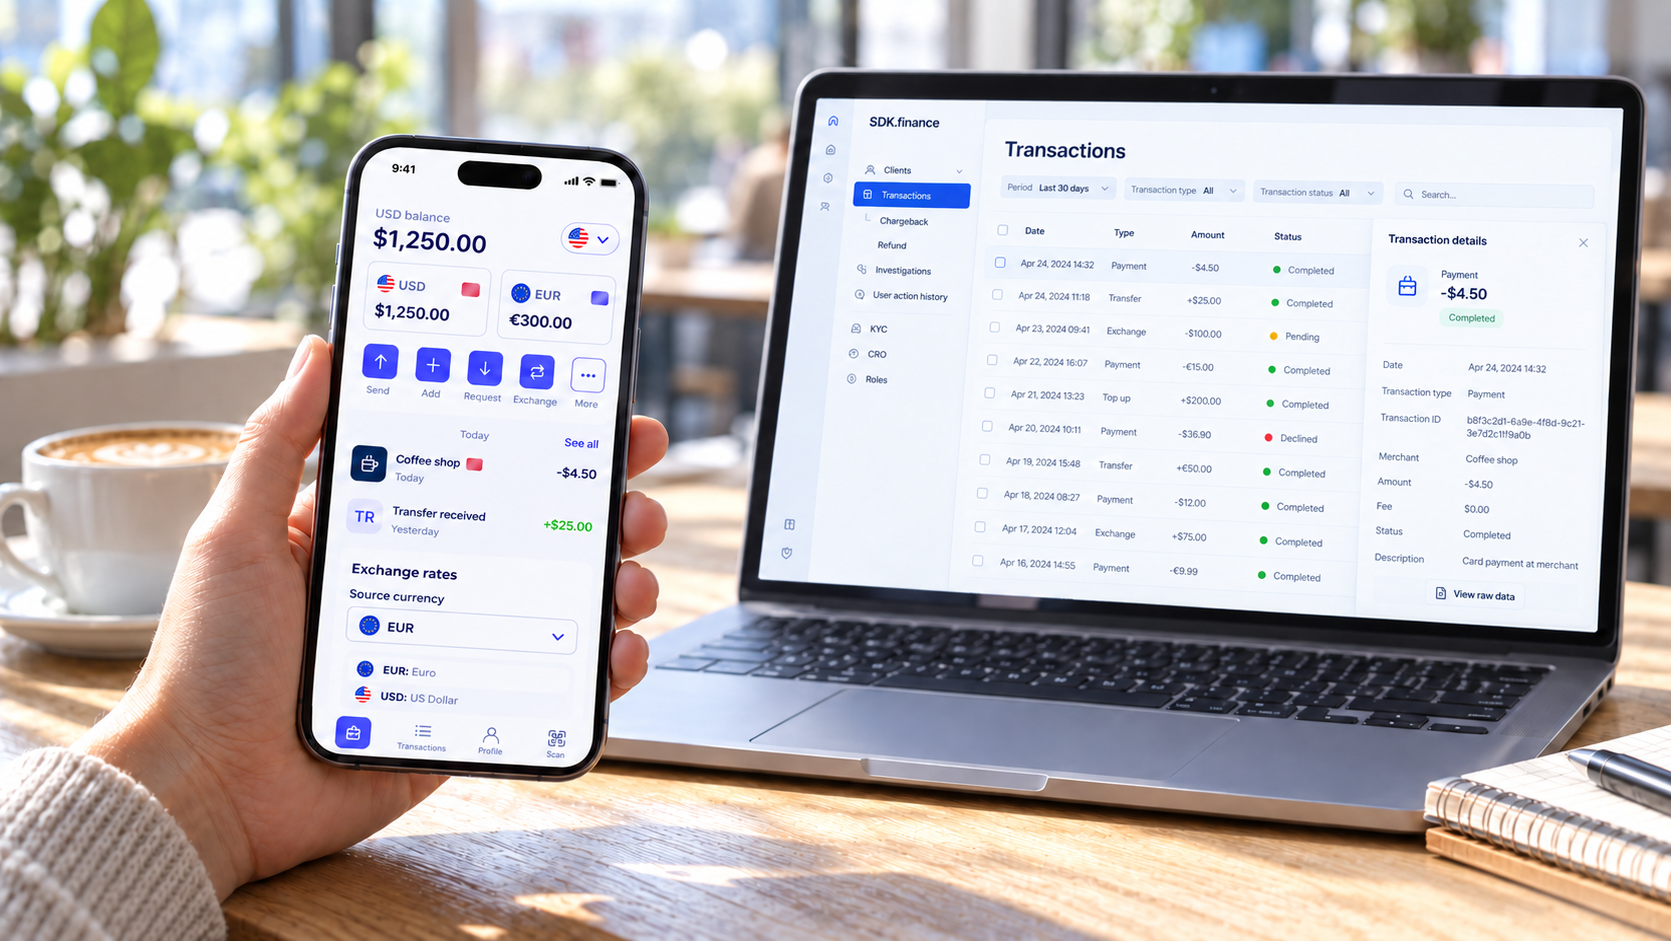
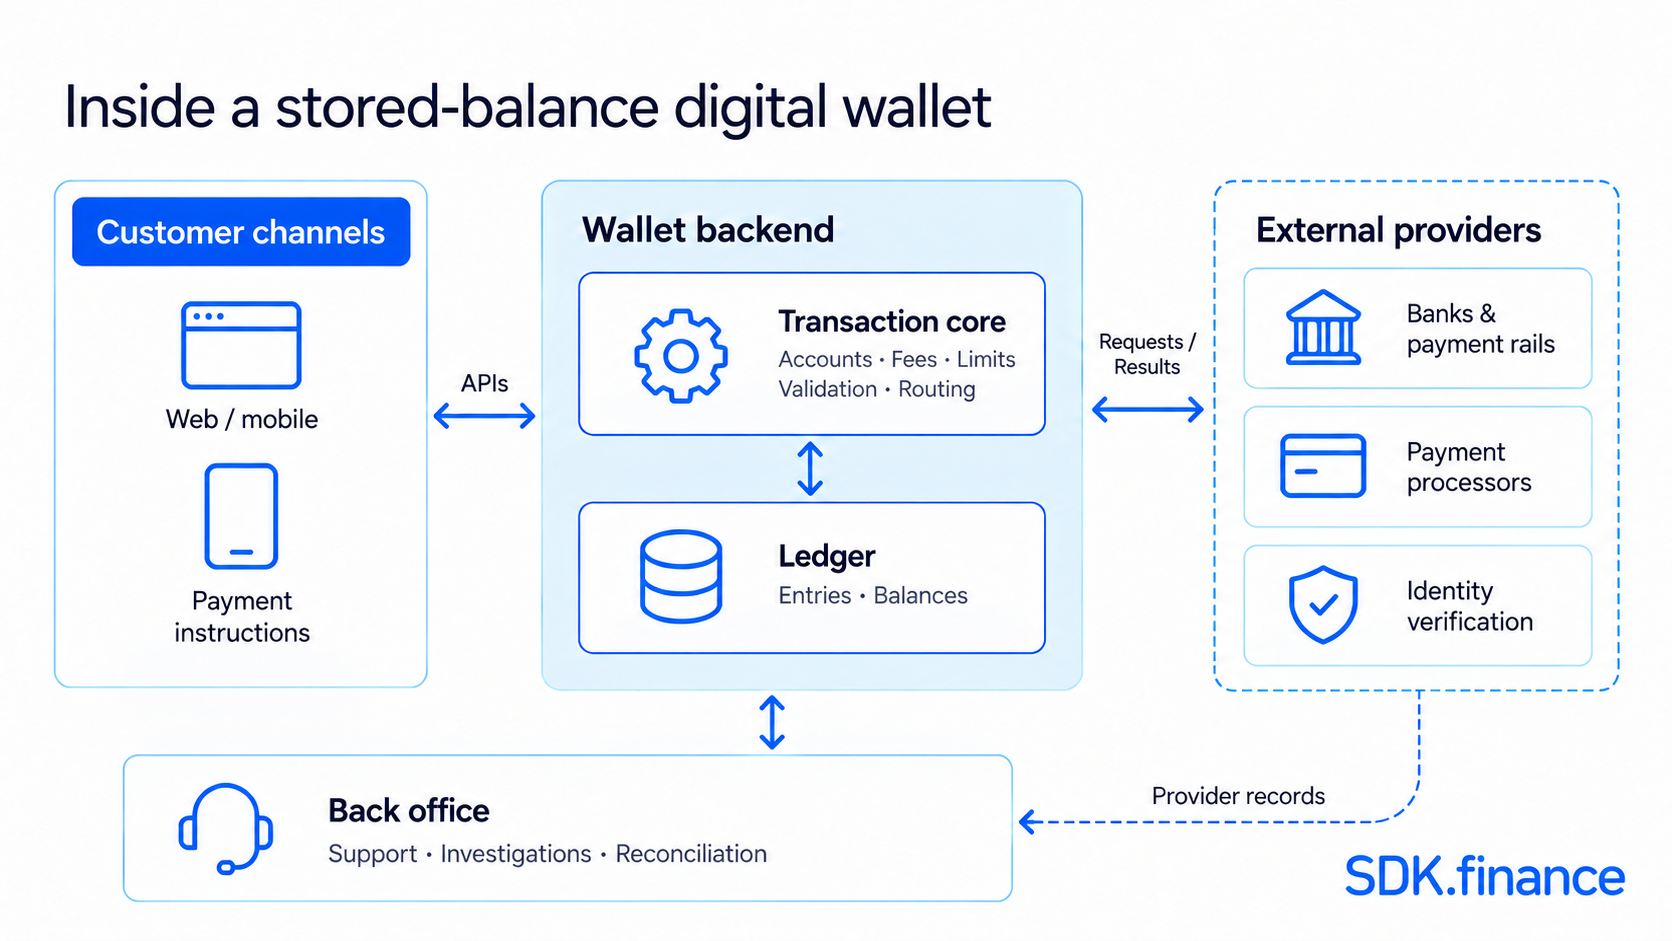
A stored-balance wallet runs on a backend system that manages all the accounts, balances, and transactions. It connects to other systems through something called APIs (basically a bridge that lets different apps talk to each other).
For linked-card wallets, APIs also connect the wallet, token service, and issuer during card provisioning.
For stored-balance wallets, backend APIs handle tasks such as:
- Creating new users and checking their info
- Managing money and transactions
- Managing customer top-ups and withdrawals
- Linking to banks or payment processors
Many wallets are built with an API-first mindset, meaning functions such as payments, transfers, and balances can also be accessed through APIs. This makes it easier to plug wallets into other services like banking apps, online stores, or even mobile operators.
Behind the curtain, the architecture can be modular. One part handles AML checks, another manages currency exchange, and another sends customer notifications. These parts can communicate using systems like Kafka or RabbitMQ, so when something happens (such as a customer transfer), connected services can respond.
The ledger records financial movements, while reconciliation compares internal records with bank or payment-provider data. These controls help teams investigate mismatches and keep balances consistent.
Security and compliance
Security isn’t an add-on here; it’s absolutely essential. These wallets deal with sensitive data and actual money, so they need several layers of protection.
You’ll usually find:
- Encryption: TLS protects data in transit. Sensitive data stored by the wallet needs appropriate protection, while tokenisation can reduce exposure of card details.
- Authentication: Users confirm payments with PINs, passwords, or biometrics. Device binding can provide an additional layer of account protection.
- Hardware protection: Phones often use secure elements or trusted environments to keep cryptographic keys safe.
- Compliance controls: Card-data security obligations and identity or financial-crime checks depend on the service, data handled, and jurisdiction. They are not identical for every wallet model.
Many backends also use Hardware Security Modules (HSMs) to handle encryption keys and go through regular security testing to stay ahead of potential threats.
Plan for ongoing software updates, transaction alerts, and account recovery when a customer loses a device. Tokenisation can limit exposure of card details, but it does not prevent every scam or protect an account whose credentials have been compromised.
Real-time and scalable operations
As transaction volumes grow, the backend needs to maintain consistent balance records and responsive APIs under load. Capacity planning should cover both transaction processing and external-provider dependencies.
To make that happen, systems can rely on:
- Optimised databases and caching
- Asynchronous, event-based processing
- Horizontal scaling (basically, adding more machines when demand spikes)
Actual throughput depends on the architecture, infrastructure, integrations, and workload. A fast balance update does not guarantee instant settlement on an external payment rail.
Ready backend, APIs, and integrations
Talk to Our TeamThe main types of digital wallets
For a business building a wallet, the model determines where customers can pay, how funds or credentials are managed, and which integrations are needed.
These categories describe different characteristics and can overlap: a mobile wallet can also be closed-loop, for example.
1. Closed-loop wallets
Used within one company’s ecosystem, like the Starbucks app. Customers load money, spend within that ecosystem, and may earn rewards. For the operator, acceptance is limited to its own network.
2. Semi-closed wallets
These work across a network of merchants that have partnered with the provider. Customers can shop or pay bills, but cash withdrawals may be restricted. The operator must define merchant participation and supported payment routes. The term and permitted functions vary by jurisdiction.
3. Open wallets
These support broader payment acceptance and may allow transfers or withdrawals through financial partners. Availability depends on the provider, market, and account terms; it does not mean the wallet works everywhere.
4. Cryptocurrency wallets
One of the most important FinTech app features is wallet flexibility, allowing users to choose between custodial wallets, where the provider manages private keys, and non-custodial wallets, where users manage their own private keys. Some FinTech applications also combine crypto and fiat wallet functionality, enabling users to manage and view their digital and traditional assets within a single platform. These wallets manage access to blockchain assets rather than storing the assets inside the app.
5. Mobile money wallets
Huge in places like Kenya, with services like M-Pesa. They’re tied to mobile numbers and let users send and receive money even without a bank account or mobile internet access, using supported telecom channels.
| Wallet model | What it manages | Payment flow and limits |
|---|---|---|
| Linked-card wallet | Linked payment-card credentials | Charges the linked card through the card issuer; acceptance depends on the wallet, card, and merchant. |
| Stored-balance wallet | Funds recorded in a wallet account | Uses the available wallet balance; funding, payments, and withdrawals depend on the provider. |
Designing funding, incoming payments, and withdrawals
- Funding: select the top-up methods your product will support, connect the relevant providers, and define when confirmed funds become available to spend.
- Incoming payments: define how senders identify a recipient and how the backend records and displays the payment status, rather than relying on a sender’s confirmation alone.
- Withdrawals: decide whether your wallet will support cash-out and through which partners. Bank transfers, agents, and ATM access each require the relevant operational setup and integrations.
Where businesses use digital wallets
Banking & FinTech
Banks use them as the face of digital banking, for transfers, onboarding, and managing accounts.
Retail & eCommerce
Retailers can build wallets around repeat purchases and loyalty programmes, with payment acceptance connected to their checkout.
Crypto
Crypto businesses can bring fiat and digital-asset services into one product. The wallet design must distinguish balance records from custody and exchange services supplied through the relevant infrastructure.
Super Apps
Super apps bring services such as transport, food delivery, and shopping together, with a shared wallet connecting payments across the ecosystem.
Telecom & Financial Inclusion
In emerging markets, mobile wallets help people without bank accounts access digital money safely.
Benefits of digital wallets
| Business benefit | Product capability and dependency |
|---|---|
| Less reliance on cash handling | Digital funding and payment flows can reduce cash collection and handling where customers and merchants adopt them. |
| Support for repeat purchases | Wallet balances, loyalty points, and rewards can connect payments with reasons to return to the business. |
| Visibility into payment activity | Transaction records and reporting help operations teams track volumes, statuses, and payment issues. |
| Additional revenue options | Configured fees, currency exchange, and partner services can support revenue, subject to provider costs and commercial terms. |
The value of digital wallets depends on the use case and operating model. These benefits should inform the initial product scope, while provider fees, integration work, and ongoing support affect the business case.
Limitations to consider
Acceptance varies by merchant, country, card issuer, and device. A compatible terminal does not guarantee that every wallet or card will work. Connectivity requirements also vary: some contactless payments can work without mobile internet, while setup, transfers, and other features may need a connection.
Fees for funding, withdrawals, or currency conversion depend on the service and payment method. When building a wallet, evaluate provider pricing and supported payment routes alongside account recovery and customer support. These dependencies should inform the product scope and partner selection.
Building a digital wallet: skills that matter
Creating a digital wallet is not a straightforward coding project. It’s an undertaking that blends technology, finance, and compliance, each with its own depth. To build a wallet that works reliably at scale, a team needs a rare mix of engineering know-how and an understanding of how money moves through regulated systems.
Key areas of competence usually include:
- Frontend and mobile engineering to design an intuitive user interface.
- Backend development and payment routing for ledger management and fund flows.
- Cybersecurity to protect data and prevent fraud.
- API design and integration for banks, processors, and external partners.
- User experience design focused on simplicity and trust.
Equally important is the regulatory side. The operator needs to identify the requirements that apply to its services, customers, and markets. Areas to assess include:
- PCI DSS scope where cardholder data is handled.
- Data-protection rules, including GDPR where applicable.
- Applicable payment-services and electronic-money rules in the target jurisdiction.
- KYC and AML controls to prevent identity misuse and financial crime, where required.
These requirements need operational processes, suitable providers, and legal review. A software foundation can support the workflows, but it does not supply a financial licence or make the finished service automatically compliant.
Launching a wallet without starting from scratch
Developing a digital wallet system entirely in-house can become a long and costly exercise. Teams need to build backend logic, set up integrations, and align the product with their operational and compliance requirements.
One alternative is a pre-built FinTech core for account management, transactions, verification workflows, and reporting. It can reduce the amount of foundational software a team must build. The time and cost saved depend on the launch scope, customisation, integrations, and regulated partner setup.
SDK.finance: the foundation for digital wallet development
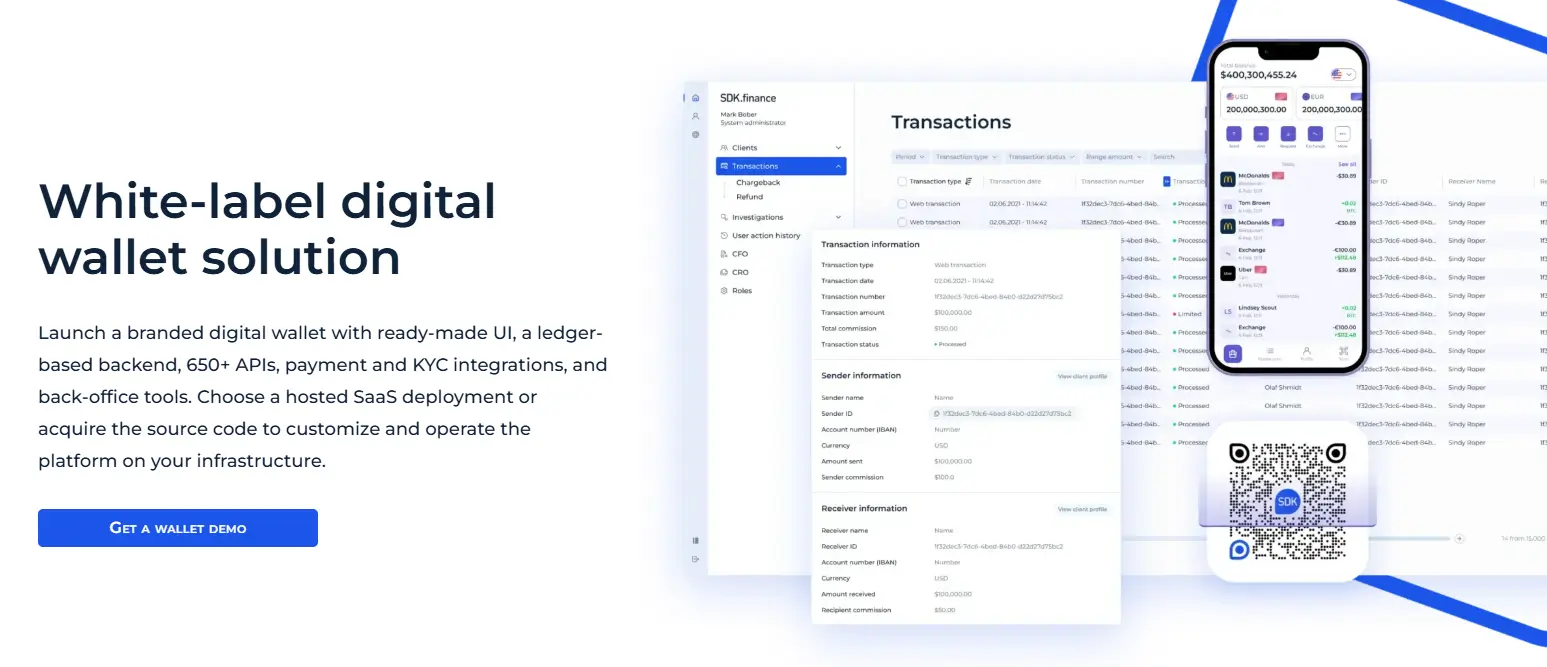
SDK.finance is a FinTech software provider that helps businesses build digital wallets and payment products. Its digital wallet solution provides a ledger-based backend, APIs, and back-office tools for managing wallet accounts, balances, transfers, and payments. Businesses can use this foundation to build a standalone digital wallet or embed wallet functionality into an existing product.
Instead of developing wallet infrastructure from scratch, businesses can configure the software, customise the user experience and connect the required KYC, banking and payment providers. SDK.finance provides the technology foundation; regulatory licences and financial services remain the responsibility of the business and its licensed partners.
With SDK.finance, you can offer your wallet users the following features, depending on your chosen configuration, integrations, and market requirements:
- In-app onboarding. Let users submit their details and identity documents in the app, with verification handled through your configured KYC process and providers.
- Multi-currency accounts. Give users access to multiple balances and currency exchange using configured currency pairs, rates, and exchange reserves.
- Crypto support. Support digital-asset balances alongside fiat accounts, with custody and crypto-to-fiat services connected through the relevant providers.
- Virtual and physical cards. Offer card issuance and management through issuer and processor integrations, subject to the card programme’s requirements.
- QR-code payments. Let users generate or scan supported payment QR codes to reduce manual entry of payment details.
- Money transfers. Enable transfers between wallet users and extend them to bank accounts or cards through the required payment integrations.
- Templates and recurring payments. Let users save transfer details and set up supported recurring payments.
- Transaction history. Help users review their spending through transaction details, statuses, amounts, and fees.
- Multilingual interface. Let users choose from the languages configured for your app.
For your business, SDK.finance provides the following tools to manage wallet operations:
- Fees and transaction limits. Configure fixed, percentage-based, or combined commissions, fee ranges, and limits by transaction amount, count, or volume.
- Currency management. Manage currencies and issuers, configure exchange pairs, and set rates manually or obtain them from an external feed.
- Customer support and KYC administration. Review customer profiles and verification documents, check activity records, and manage account status.
- Transaction oversight. View customer transactions across statuses and investigate payment issues using back-office records.
- Tariff management. Group fees and limits into contracts and assign the appropriate terms to customer segments.
- 650+ API endpoints. Connect customer interfaces and third-party services through the platform’s APIs, extending your wallet’s capabilities as requirements change.
With a source code licence, your team gets the SDK.finance core as the foundation on which to build its digital wallet. The core provides the account, ledger, and transaction-processing components that your team extends with its own product logic, user experience, and integrations, then deploys in its chosen infrastructure. The licence and implementation agreements define modification rights, maintenance responsibilities, and ownership of custom work.
MPAY case study
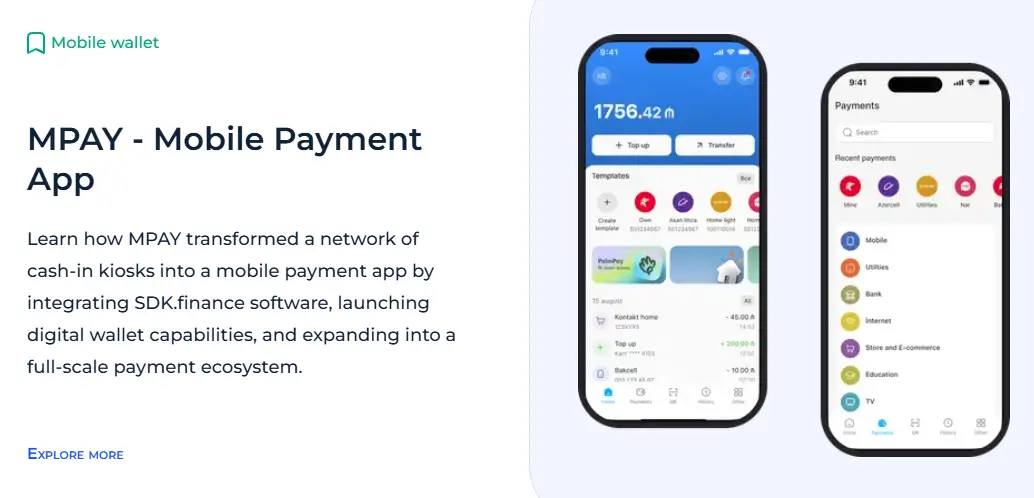
MPAY began with a network of cash-in payment kiosks across Azerbaijan and abroad. It chose SDK.finance’s ledger layer through an on-premise code purchase, then connected its kiosks and e-commerce services within a shared ecosystem and extended access to web, iOS and Android applications.
The implementation used a multi-asset ledger, back-office account administration, role-based access and payment gateway integration. This provided the foundation for managing customer accounts, service providers and currencies across channels. The MPAY case study explains how the ledger and integrations supported that expansion.
Choosing a foundation for your digital wallet
Digital wallets connect the user’s payment instruction to the systems that authorise, record, and complete it. Understanding whether a product uses a linked card, a stored balance, or another model is the starting point for designing its architecture and choosing financial partners.
If you’re building a new wallet product, define the required payment flows, integrations, and operational responsibilities before selecting the software foundation.
Ready backend, APIs, and integrations
Talk to Our Team