Building a FinTech product in Kenya starts with understanding how people and businesses already move money, and where those services still fall short. The landscape spans mobile money, merchant payments, digital credit, asset finance, and cross-border transfers. For founders and financial institutions, the opportunity is to solve a specific customer problem with a service that fits local payment habits and can operate reliably.
This article examines Kenya’s FinTech market, the companies shaping its ecosystem, and the opportunities and operating considerations for new products. We also look at SDK.finance, a FinTech software provider that supplies the software foundation for building financial products such as digital wallets, merchant payment platforms, remittance services, and digital banking products.
Discover how the SDK.finance TPS can power high-speed, secure operations across banking, fintech, and retail
Talk to Our TeamKenya FinTech market size and overview
How to measure the market
Market size depends on what is being measured. CBK’s mobile money statistics describe registered accounts and agent transaction flows; FinAccess measures household access and usage; Partech tracks technology investment. These indicators show different dimensions of the ecosystem and cannot be added together or treated as total FinTech revenue.
Kenya’s mobile money infrastructure extends beyond customer apps to a large cash-in and cash-out network. In August 2026, the Central Bank of Kenya recorded 95.31 million registered mobile money accounts and 563,605 active agents. Agents handled KSh 761.13 billion in cash-in and cash-out transactions that month. Registered accounts are not unique customers, and agent cash flows cover only part of payment activity.
| Indicator | Reported figure | Period and scope |
|---|---|---|
| Formal financial access | 84.8% | 2024 FinAccess survey; adults in Kenya. |
| Registered mobile money accounts | 95.31 million | August 2026; registered accounts across providers, not unique people. |
| Agent cash-in and cash-out value | KSh 761.13 billion | August 2026; monthly cash flows through agents. |
| Technology funding | US$1.04 billion | Calendar 2025; equity and debt across Kenya’s technology sectors. |
Growth of digital and card-based payments
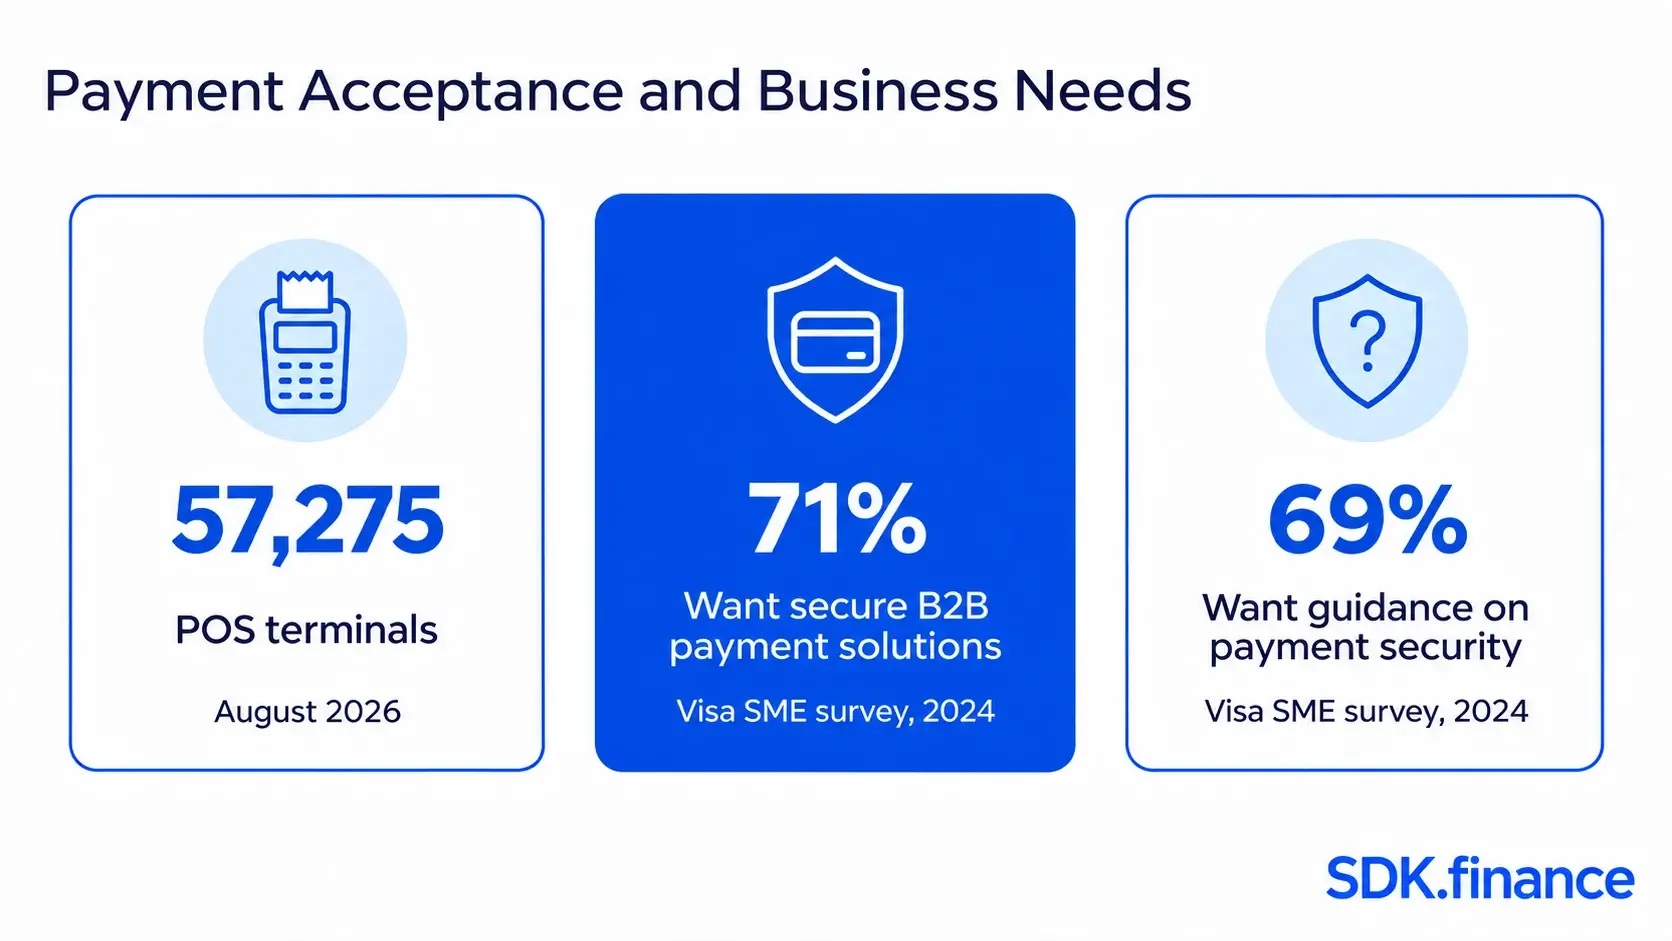
Kenya’s card-acceptance infrastructure expanded to 57,275 point-of-sale terminals in August 2026, compared with 52,188 in August 2025, according to CBK. That is an increase of approximately 9.7%, calculated from the reported counts. The figures measure terminals rather than unique merchants or payment value. Alongside mobile money, this wider acceptance network gives businesses more ways to receive customer payments.
FinTech and payment gateway innovation
Merchant demand gives payment providers a clearer direction for innovation. In Visa’s October 2024 study of 254 business owners and store managers in Kenya, 71% of respondents already accepting digital payments wanted secure B2B payment solutions, while 69% wanted guidance on payment-security practices. These are findings from the surveyed businesses, not market-wide adoption rates.
For gateways and business payment platforms, the opportunity is to combine payment acceptance with practical services: clearer payment status, records that connect collections to invoices, and dependable support when a transaction fails. Providers such as Pesapal and Cellulant operate in this area. The Visa findings support a focus on security and business usability; they do not measure either provider’s market share.
FinTech companies in Kenya
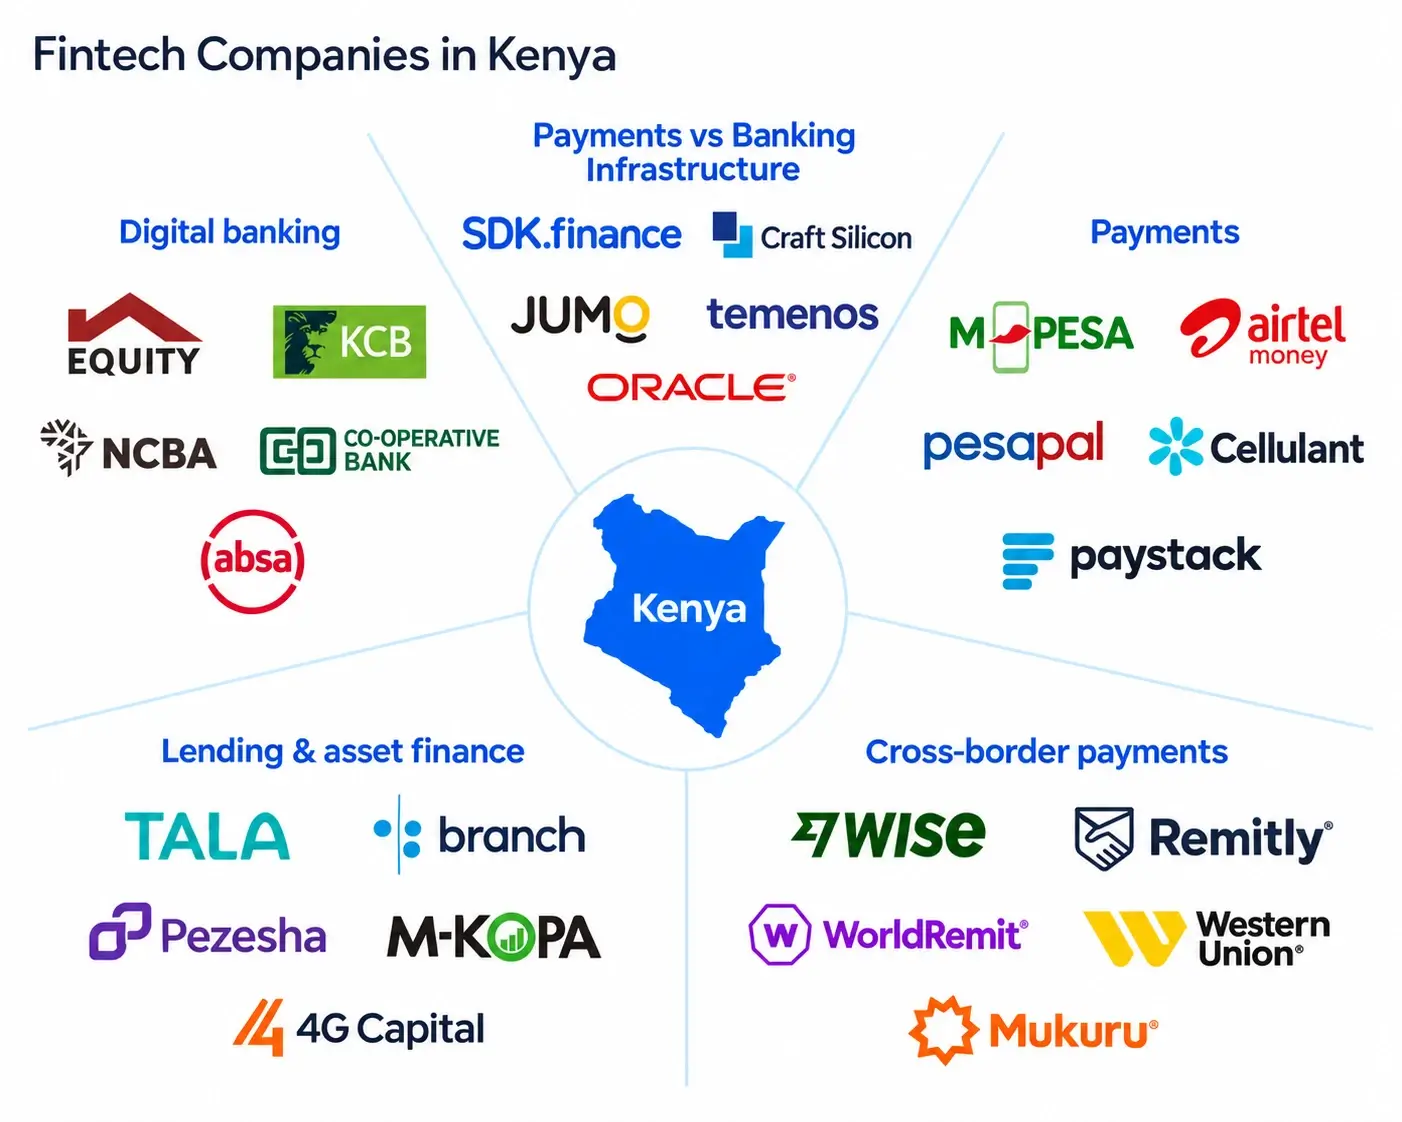
The companies below cover consumer services, merchant payments, software infrastructure and business financing.
| Company | Business category | Role and example use |
|---|---|---|
| SDK.finance | Payments & Banking software foundation | Payments & Banking software foundation for launching products that move money: neobanks, digital wallets, mobile money, remittance, and payment systems; product offerings include the Transaction Platform and General Ledger. |
| Safaricom M-PESA | Mobile money | Transfers, merchant payments, and business collections for individuals and businesses; for example, receiving customer payments through M-PESA. |
| M-KOPA | Asset finance | Smartphone financing for customers paying in instalments; for example, acquiring a device without paying its full price upfront. |
| Tala | Digital lending | App-based loans for individual borrowers; for example, applying for credit, receiving approved funds through M-PESA, and managing scheduled repayments. |
| Cellulant | Payment infrastructure | Tingg payment infrastructure for businesses collecting and disbursing funds; for example, managing customer collections and business payouts through one service. |
| Pezesha | SME finance and credit infrastructure | Working-capital finance and credit infrastructure for small businesses and partner platforms; for example, offering business loans through an existing commercial relationship. |
| JUMO | Financial services technology | Technology for banks and payment partners delivering financial products; for example, bringing credit services to customers through established distribution channels. |
| Kopo Kopo | Merchant payments and credit | Payment acceptance, outgoing transfers, and credit for eligible merchants; for example, collecting Lipa na M-PESA payments and paying suppliers. |
| AZA Finance | Cross-border payments and FX | International payments and currency exchange for businesses; for example, paying overseas suppliers through supported currencies and payment routes. |
| Branch | Digital lending | Digital credit for individual borrowers in Kenya; for example, applying for a loan and managing repayment through a digital channel. |
| Pesapal | Merchant payment acceptance | Online and in-person payment acceptance for merchants; for example, collecting customer payments through an online checkout or point-of-sale service. |
| Lendable | Asset-backed debt | Debt financing for eligible FinTech businesses; for example, funding expansion by consumer lenders, SME lenders, asset-finance businesses, and payment companies. |
SDK.finance
SDK.finance provides a payments and banking software foundation for teams launching financial products in Kenya. Operating since 2013, the company is a PCI DSS Level 1 compliant service provider. Its clients include businesses that have built and launched products for the Kenyan market on the SDK.finance platform.
Safaricom M-PESA
Safaricom M-PESA provides mobile money services for individuals and businesses in Kenya. Its offering combines money transfers with merchant payments and business collections. For a retailer, the practical use is receiving customer payments; for a product team, M-PESA represents a payment service to consider within the wider customer journey.
M-KOPA
M-KOPA provides smartphone financing through instalment payments, helping customers access a device without paying its full price upfront. Its offering combines the financed asset with a repayment arrangement. In Kenya’s FinTech landscape, it illustrates how asset finance can connect a physical product, customer access, and ongoing digital payments.
Tala
Tala provides app-based credit to individual borrowers in Kenya, with approved loans paid to M-PESA. Its service centres on applying for credit and managing repayment through a digital journey. For customers, the relevant comparison includes eligibility, the amount offered, the full repayment cost, and the repayment schedule.
Cellulant
Cellulant provides payment infrastructure through Tingg for businesses collecting and disbursing money. Its Kenyan offering serves merchants and organisations that need payment services within their commercial operations. A relevant use case is coordinating customer collections and business payouts, with supported payment methods and settlement arrangements determined by the service agreement.
Pezesha
Pezesha combines working-capital lending for small businesses with credit infrastructure for partners. Its offering serves both enterprises seeking finance and platforms that want to include lending within an existing business relationship. In Kenya, this makes it relevant to small-business funding and to the delivery of credit through partner channels.
JUMO
JUMO provides technology for financial products delivered in partnership with banks and payment providers. Its offering supports institutions bringing financial services to customers through existing distribution relationships. The practical model brings together a financial institution, a distribution partner, and a technology provider, with each contributing a different part of the service.
Kopo Kopo
Kopo Kopo provides payment and credit services for businesses in Kenya. Merchants can accept Lipa na M-PESA payments, manage outgoing transfers, and track transactions through its business tools. Eligible businesses can also access credit, making the service relevant to retailers managing customer collections, supplier payments, and working-capital needs.
AZA Finance
AZA Finance provides business payments and foreign-exchange services across African markets. Its offering is relevant to companies paying suppliers or moving funds between currencies. For a Kenya-focused business, the useful comparison is the specific payment route, supported currencies, settlement arrangements, and legal entity providing the contracted service.
Branch
Branch provides digital credit services to borrowers in Kenya and appears in the Central Bank of Kenya’s digital-credit provider directory. Its offering centres on accessing loans through a digital channel. A customer assessing the service should consider the available loan offer, repayment schedule, total cost, and support arrangements.
Pesapal
Pesapal provides online and in-person payment acceptance for merchants. Its offering serves businesses that need to collect customer payments across different sales channels. A retailer can assess its checkout and point-of-sale options together, comparing supported payment methods, settlement arrangements, and how payment records fit the business’s daily operations.
Lendable
Lendable provides asset-backed debt financing to FinTech businesses in emerging and frontier markets, with an office in Nairobi. Its qualifying sectors include small-business lenders, asset lenders, consumer lenders, and payment companies. The relevant use is financing business expansion through debt facilities, with eligibility and terms assessed against the borrower’s financial position.
Key FinTech trends and opportunities in Kenya
More frequent use of mobile money
Kenya’s mobile money agents handled 227.41 million cash-in and cash-out transactions in August 2026, compared with 221.13 million in August 2025, according to CBK’s payment statistics. This represents approximately 2.8% year-on-year growth. These figures measure transactions through agents, rather than unique users or the full volume of mobile money payments.
Everyday payments for small businesses
For a small merchant, accepting a digital payment is only one part of the job. A useful product could connect collections to invoices, show which customers have paid, and make settlement amounts and fees easier to reconcile. Test demand for these workflows with a defined merchant segment before adding more payment methods or credit features.
Access beyond an app download
Kenya’s National Financial Inclusion Strategy for 2025–2028 prioritises affordable smartphones, wider digital connectivity, and improved access to identification documents. For FinTech teams planning a Kenyan launch in 2026, these priorities highlight the importance of designing services around the devices, connectivity, and documents customers actually have. Product planning should consider assisted onboarding, accessible service channels, and customer support beyond a smartphone app.
Financial health and useful savings tools
The gap between formal access and financial health makes everyday money management a useful area to investigate. Possible product concepts include savings goals, clear spending records, and reminders that help users plan recurring payments. Validate whether these tools solve a specific problem and whether their fees remain affordable for the intended users.
Regulation and consumer protection in Kenya
The regulatory route depends on the financial activity and the entity responsible for it. Define who holds customer funds, provides credit, executes payments, and processes personal data before selecting the software and partners.
Payment services and digital credit
The Central Bank of Kenya publishes a directory of authorised payment service providers under the National Payment System framework and a separate directory of licensed digital credit providers. Use the relevant register to check the legal entity behind a proposed service or partnership. These are separate regulatory categories; a software platform alone does not confer either status.
Personal data and customer protection
The Office of the Data Protection Commissioner has published financial-sector guidance covering financial-data processing, customer privacy, and related obligations. Product teams should map the personal data they collect, its purpose, access permissions, and the providers that receive it. Build clear pricing, payment confirmations, and a route for resolving complaints into the customer journey.
Discover how the SDK.finance TPS can power high-speed, secure operations across banking, fintech, and retail
Talk to Our TeamKenya’s FinTech funding landscape
Kenya attracted US$1.04 billion in technology funding in 2025, according to Partech’s Africa Tech VC report. The figure covers equity and debt across Kenya’s technology sectors, rather than FinTech alone. It provides context for fundraising but does not establish the capital available to an individual startup.
From seed to Series A
A funding case needs to connect the customer problem with evidence of a repeatable business model. Payment businesses should explain transaction economics, merchant retention, and operating costs. Lending businesses should explain portfolio quality, the cost of funding, and repayment performance. These measures make the next funding milestone more concrete than a general plan to expand.
Key funding challenges for FinTech startups in Kenya
Capital runway and investor fit: estimate the cash needed to reach the next measurable milestone, then approach investors whose sector, stage, and investment size match the business. Prepare evidence of customer demand and a clear use of funds.
Debt and financial readiness: model interest, fees, repayment dates, and currency exposure together. Foreign-currency borrowing creates an additional risk when revenues are in Kenyan shillings. Reliable financial records, ownership documentation, and a defined regulatory model are also practical preparation for due diligence.
Addressing the funding gap: what’s next?
Match the financing route to what the capital will fund. Equity can support product development and expansion; debt needs a credible repayment source and a suitable match with cash flows. Compare the reporting requirements, costs, and control implications of each offer before committing.
Industry networks can support introductions and partner research. The FinTech Association of Kenya and Africa Tech Summit Nairobi are examples of places to identify relevant organisations. Assess any funding programme against its current eligibility criteria and available capital rather than treating an announcement as an accessible financing offer.
How to start a FinTech company in Kenya
Starting a FinTech company in Kenya requires balancing regulation, infrastructure, and local market dynamics. The ecosystem is well-developed, especially in mobile money, but access to existing rails still depends on provider agreements, technical integration and the operating model.
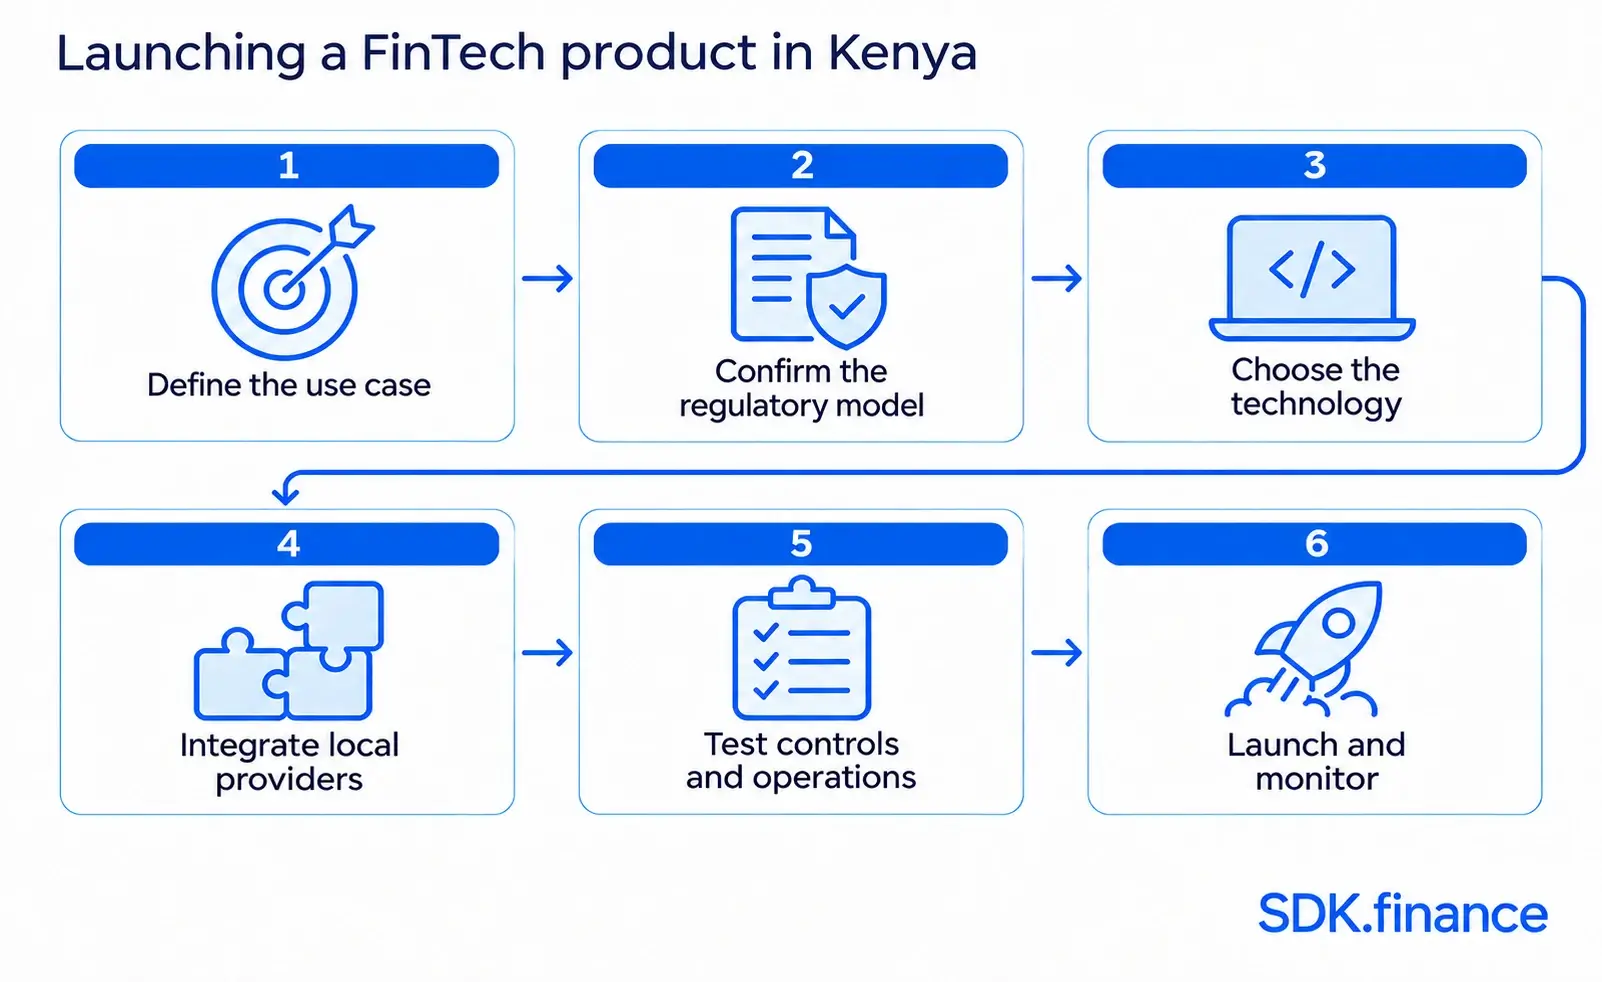
In practice, teams need to work through the following decisions:
- Define a focused use case: payments, wallets, lending, or embedded finance. Identify the customer problem and the transactions the product will support.
- Confirm the regulatory model: establish which entity provides the regulated service, holds customer funds or extends credit. Check the applicable CBK requirements and other relevant obligations before launch.
- Choose the technology: define the ledger, wallet, transaction-processing, customer-channel and back-office requirements, then decide which components to build or procure.
- Integrate local providers: connect mobile money, banks and identity-verification services as required. Agree responsibilities for callbacks, failed transactions, refunds and reconciliation.
- Test controls and operations: validate customer onboarding, permissions, transaction limits, exception handling and support processes with the relevant teams and providers.
- Launch and monitor: track transaction success, reconciliation differences, customer issues and operating costs. Expand only when the initial service is working reliably.
Payment services and digital lending have separate CBK registers. A software supplier is a different participant from the entity authorised to provide financial services. The required permissions and any partner arrangement must therefore be assessed for the actual product and money flow.
What comes next for FinTech in Kenya
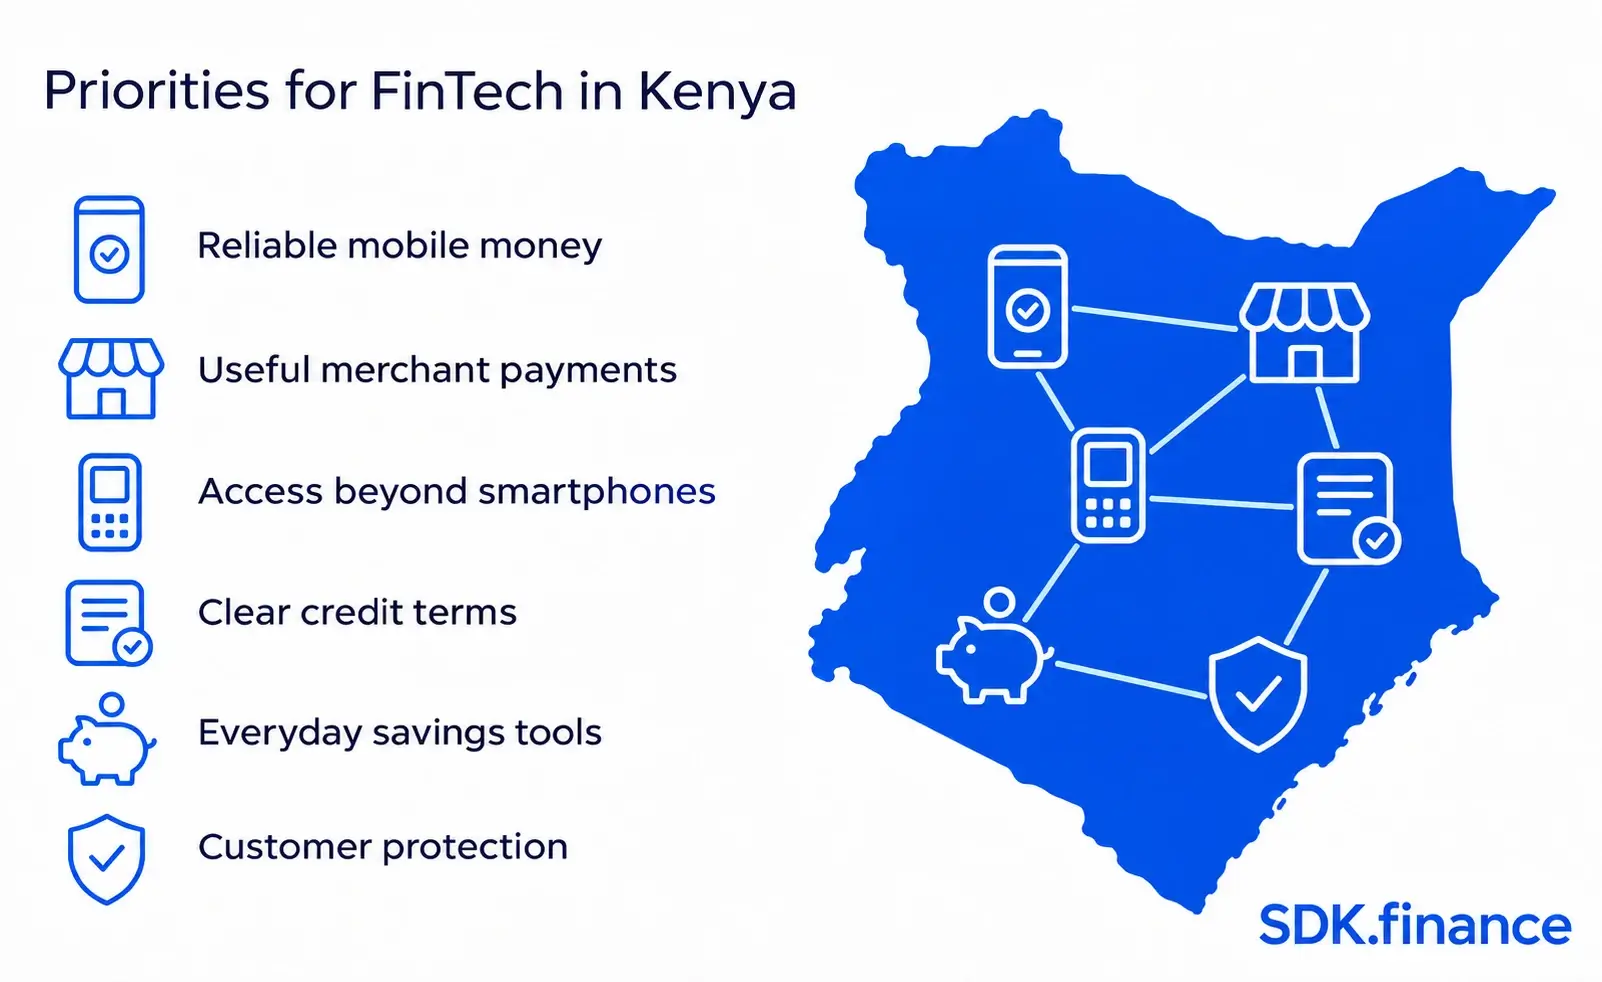
The next phase of FinTech in Kenya should be judged by how well services work in everyday life. The priorities below turn the market’s opportunities into practical questions for product teams.
From payment acceptance to useful business tools
For merchants, the next step is to connect incoming payments with the work that follows: identifying the customer or invoice, checking fees, paying suppliers, and resolving failed transactions. A product should make these tasks easier across the payment methods a business actually uses. Teams can measure progress through repeat usage, fewer unresolved payment issues, and clearer transaction records.
Broader access and better financial outcomes
Expanding access means testing the whole customer journey, including the device, identification, assistance, and cash access a person needs. Assisted channels and simpler journeys deserve consideration alongside smartphone apps. For credit and savings products, focus on clear repayment terms, understandable charges, and tools that help customers plan regular expenses. Evaluate whether people continue using the service and understand its costs, rather than treating registration alone as success.
Trust as part of the service
Customer protection should be visible in the product: clear payment confirmations, transparent fees, appropriate access controls, and a practical route to support. Before expanding, teams should test how they handle a disputed payment, a lost phone, or an incorrect transfer. Reliable responses to these situations can be as important to the customer experience as adding another feature.
Why SDK.finance is a strong fit for launching a FinTech product in Kenya
SDK.finance gives FinTech teams a ready-made transaction core for launching digital wallets, merchant payment products and marketplace payment services in Kenya. The Transaction Platform brings together customer and business accounts, balances, payment workflows, built-in accounting and back-office tools. With 650+ APIs, teams can build their own customer experience around that core. SDK.finance has been building payment and banking software since 2013 and lists Kenya among its client markets.
A Kenyan FinTech could start with mobile money collections for a group of merchants and expand to a nationwide network on the same transaction core. Merchants could track sales and refunds across outlets, while the platform keeps merchant balances and its own fees separate. With the Source Code Licence, the team can adapt transaction logic and integrate the Kenyan payment rails it needs through the relevant providers, adding bank transfers, card payments or new payout options as the network grows.
SDK.finance is a PCI DSS Level 1 compliant service provider. Its software development practices and security governance were independently assessed under PCI DSS v4.0.1. Each operator remains responsible for compliance across its own cardholder data environment.
SDK.finance was a finalist at both the PayTech Awards and the Banking Tech Awards in 2025 and 2026. In 2026, Everest Group included SDK.finance in its Top 50™ Core Banking Technology Providers report, confirming its Everest Group recognition. Market.us also featured the company as a leading provider in its Core Banking Systems Market report.
Building for Kenya’s FinTech market
Kenya’s FinTech opportunity spans mobile money, merchant payments, lending and the infrastructure behind those services. The FinAccess findings show why access and financial health should be assessed separately, while Partech’s funding figures distinguish the wider technology market from FinTech alone.
For founders and financial institutions, the next step is to turn the market overview into a focused product plan: identify the customer, compare relevant providers, confirm the regulatory model and define the technology and operational requirements. This makes the opportunity easier to assess before committing to development or expansion.
Discover how the SDK.finance TPS can power high-speed, secure operations across banking, fintech, and retail
Talk to Our Team