Starting a digital bank in 2026 is not just a technology challenge. It is a licensing, compliance, infrastructure, and operations challenge. Most teams that fail do so not because they could not build an app, but because they underestimated what regulated financial infrastructure actually requires. A real-time ledger, AML controls, card processing, fee management, multi-currency operations, and audit-grade reconciliation are not optional extras. They are the minimum.
The path is clearer than it used to be. Proven licensing models exist at every level of ambition, from a sponsor-bank MVP to a fully licensed digital bank. Ready fintech platforms like SDK.finance reduce the infrastructure burden dramatically, especially when the team wants speed without giving up long-term technology control.
This guide covers licensing options, realistic costs, technology architecture, step-by-step launch sequence, build versus buy decisions, and how SDK.finance fits as a platform foundation for a digital bank, neobank, or banking-adjacent fintech product.
Quick Answer: How Do You Start a Bank?
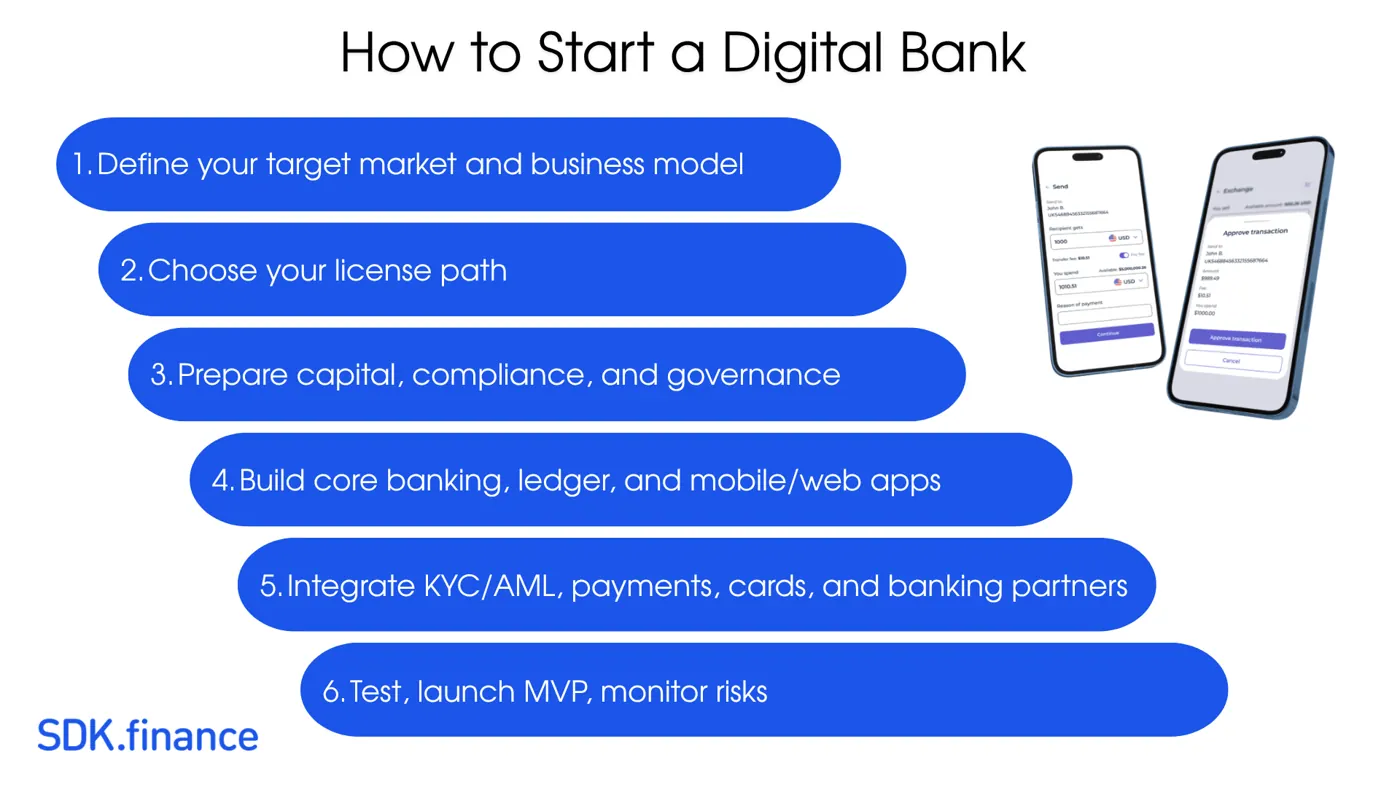
- Define your target market and business model. Pick a narrow wedge – SMBs, migrants, freelancers, marketplaces, or another segment with a clear financial pain.
- Choose your license path. Full bank charter, EMI/PI license, or sponsor bank/BaaS partnership. Each has different capital requirements, timelines, product constraints, and economics.
- Prepare capital, compliance, and governance. Outsourcing technology or infrastructure does not remove regulatory accountability. You need real compliance ownership from day one.
- Build core banking, ledger, back office, and mobile/web apps. This is where a platform like SDK.finance can compress the timeline versus a custom build.
- Integrate KYC/AML, payments, cards, and banking partners. The integration layer usually takes longer than teams expect.
- Test, launch MVP, monitor risk and operations. Activation rate, KYC pass rate, payment success rate, fraud loss ratio, reconciliation breaks, and complaint rate matter from day one.
SDK.finance provides core banking infrastructure with ledger, payments, wallets, ready applications and flexible deployment options
Talk to Our TeamDigital Bank vs. Neobank vs. Fintech App
The terminology varies by market, but the meaningful distinction is regulatory and economic: who holds the license, who is responsible for safeguarded or insured funds, and what revenue model the product can legally support.
| Type | License holder | Deposit-taking | Lending | Launch speed | Best fit |
| Fully licensed digital bank | Own bank charter | Yes, subject to local deposit-protection rules | Yes | 2-4 years | Long-term full-stack banking |
| EMI/PI neobank | Own EMI or PI license | No bank deposits; safeguarded e-money | No or limited | 6-18 months | Wallets, cards, transfers, FX |
| Sponsor bank/BaaS neobank | Sponsor bank or licensed partner | Via partner structure | Via partner | 6-12 weeks for MVP | Validation and fast market entry |
| Fintech app | No direct license; relies on partners | No | No | Weeks | PFM, payments UX, referral products |
The most important point is economic. Card-led consumer neobank models often need additional revenue layers – subscriptions, FX, SME services, lending where licensed, payment processing, or embedded finance – because interchange alone rarely supports a durable business.
Main License Paths for Launching a Digital Bank
The licensing strategy should follow the maturity of the business, not the ambition of the brand. A full banking license gives the most control, but it is rarely the right first step for a fintech MVP. A sponsor-bank or BaaS model is usually the fastest route to market. An EMI or PI license is often the best middle path for payments, wallets, cards, FX, and multi-currency products. A full bank charter starts to make sense only when deposit-taking, lending, and balance-sheet economics become central to the business model.
| Strategy | Best when | Main trade-off |
| Start with sponsor bank/BaaS | You need to validate demand quickly and reduce regulatory capital requirements at MVP stage. | Fastest route, but creates partner dependency and less control. |
| Move to EMI/PI license | The product has traction and is focused on payments, wallets, cards, FX, or multi-currency accounts. | More control than BaaS, but still not a full deposit-taking bank. |
| Apply for full bank charter | Deposits, lending, net interest margin, and primary banking relationship are core to the business. | Maximum control, but highest capital, governance, and timeline burden. |
Full banking license
A full bank charter gives the widest product surface:
- deposit-taking,
- balance-sheet lending,
- and net interest margin.
It is also the most demanding path.
In the US, a new bank normally needs approval from a chartering authority and deposit insurance from the FDIC; the Federal Reserve notes that starting a bank can take a year or more and usually involves more than one regulator.
In the UK, the Bank of England/PRA new bank authorisation process provides a structured route, including mobilisation for firms that need to complete build-out under restrictions.
This path is best for teams that need direct deposit-taking, lending from their own balance sheet, and maximum control over the financial relationship. It is rarely the fastest path for a fintech MVP.
EMI or Payment Institution license
An EMI or PI license is often the most practical starting point for a payments-led digital banking product. It can support:
- wallets,
- cards,
- transfers,
- payment accounts,
- FX,
- and other payment services, depending on jurisdiction and license scope.
It does not automatically allow deposit-taking or bank-style balance-sheet lending.
In the EU, PSD2 sets different initial-capital thresholds for payment institutions depending on services, while e-money institutions are subject to a higher initial-capital requirement. The European Banking Authority provides the regulatory framework context for payment services and e-money. In the UK, the FCA regulates payment and e-money institutions, with increasingly strict safeguarding and reconciliation expectations.
Sponsor bank or Banking-as-a-Service partnership
BaaS is a commercial and technical delivery model, not a license type. It lets a digital banking team launch on top of a partner bank or regulated provider while operating the customer-facing product layer. It can be fast and capital-efficient, but it creates dependency on the sponsor’s compliance requirements, pricing, technical capabilities, risk appetite, and strategic direction.
The right sequence for many teams is: BaaS for product validation, EMI/PI once product-market fit is established, and a full bank charter only when deposits and lending become the core economic engine.
White-label or configurable banking platform
A platform like SDK.finance does not replace licensing. It provides the software foundation beneath the licensed operation. Licensing determines what you are allowed to do; your platform determines how efficiently you can do it.
How Much Does It Cost to Start a Digital Bank?
A realistic 2026 launch budget starts from $100k-$250k for a SaaS or lean MVP path and can reach $1M-$5M+ for custom or fully regulated builds. A fully licensed bank can require substantially more once regulatory capital, legal work, risk teams, audits, and operations are included.
| Model | Starting budget | Typical full budget |
| SaaS digital banking platform | $100k-$250k | $250k-$600k+ |
| Sponsor bank/BaaS MVP | $150k-$300k | $300k-$700k+ |
| EMI/PI neobank | $300k-$700k | $700k-$2M+ |
| Ready platform with source-code license | $250k-$600k | $600k-$1.5M+ |
| Custom build from scratch | $800k-$1.5M | $1.5M-$5M+ |
| Fully licensed bank | $2M-$5M+ before scale | $5M-$20M+ |
As a market benchmark, SDK.finance analyses of enterprise core banking vendors estimate Temenos at about $518,000 per year on average and FIS in a broad $300,000-$1 million annual range, confirming that core banking software costs can quickly reach hundreds of thousands of dollars per year before implementation, migration, and customization are included.
SaaS vs. source-code license: the trade-off
SaaS gives the fastest start with lower upfront cost and no infrastructure overhead. It is useful for testing transaction scenarios, validating assumptions, and launching with managed infrastructure. Source code costs more upfront but gives 100% vendor independence: your team owns the codebase, deploys in its own environment, integrates providers directly, and continues development on its own roadmap.
SDK.finance offers both. For serious fintech teams building a differentiated long-term product – especially in markets with data-residency requirements, custom compliance obligations, or deep technical ownership needs – the source-code license is the strategically stronger choice.
Step-by-Step Roadmap: How to Start a Digital Bank
Step 1. Choose a narrow market wedge
Successful digital banks do not start by being a better bank for everyone. They start with one use case where digital execution is materially better than incumbents: SME invoicing and payroll, cross-border payments for a specific corridor, salary-day money movement, embedded treasury for software platforms, or mobile-first wallets for underserved customers.
Step 2. Define business model and unit economics
Revenue can come from subscriptions, FX spread, payment processing, merchant fees, interchange, lending margins where licensed, or embedded finance platform fees. Plan unit economics before build begins. A mass-retail free-card model needs much higher volume than an SME or B2B infrastructure model.
Step 3. Select your regulatory path
A practical staged approach is BaaS MVP for validation, EMI/PI once product-market fit is established, and a full bank charter only when deposits and lending become core to the economics. Start with the lightest regulated structure that supports the first product.
Step 4. Build compliance and risk foundation
Compliance needs to be part of the product architecture: KYC/KYB, AML/CTF, sanctions and PEP screening, transaction monitoring, suspicious-activity workflows, audit logs, data retention, complaint handling, and reporting.
Step 5. Choose core banking and ledger architecture
A digital bank needs a reliable ledger, account and wallet logic, transaction statuses, reversals, fees, limits, multi-currency support, reconciliation, and audit trails. SDK.finance provides these as a configurable fintech platform rather than a blank engineering project.
Step 6. Design customer experience
The customer layer should cover onboarding, accounts, wallets, balances, transfers, card management, transaction history, notifications, and support.
For related reading, see Mobile Banking App Development and Banking App Development: How to Create a Bank Application.
Step 7. Set up infrastructure and environments
Plan for development, pre-production, and production environments. SaaS reduces infrastructure burden. Source-code delivery gives full deployment control for teams with data-residency, security, or architecture requirements.
Step 8. Configure the system
Configuration includes currencies, providers, contracts, fees, limits, exchange rates, roles, permissions, and available operations. This is where a configurable platform saves time because business logic does not need to be hard-coded for every rule.
Step 9. Set up user management and KYC
User management covers individual and business users, document collection, verification statuses, risk levels, approvals, account restrictions, and compliance review flows.
Step 10. Connect payments, cards, and third-party providers
A digital bank usually depends on KYC providers, AML tools, sponsor banks, payment processors, card issuers, FX providers, open banking providers, analytics tools, and customer support systems. SDK.finance’s API-first architecture and provider model support this integration layer.
Step 11. Test operations before launch
Test failed payments, reversals, dispute flows, reconciliation under load, provider downtime, permission boundaries, AML alerts, support processes, and incident response. The happy path is not enough.
Step 12. Launch, monitor, and expand
Track activation rate, KYC pass/fail rate, payment success rate, card authorization rate, reconciliation breaks, fraud loss ratio, support tickets, complaint rate, revenue per active user, and retention by segment.
Build vs. Buy vs. Source Code
Build from scratch
Pros: full architectural control and proprietary IP across the stack.
Cons: long build timeline, high cost, ledger and reconciliation risk, security burden, and a maintenance load that pulls engineering effort away from differentiation.
Closed white-label platform
Pros: fast time to market.
Cons: vendor lock-in, limited customization, opaque codebase, dependency on vendor roadmap and pricing, and difficult exit if the vendor changes direction.
Configurable platform with source-code ownership
This is the model SDK.finance was designed for. A ready fintech platform gives the compressed timeline of white-label software. Source-code delivery gives the customization freedom and vendor independence of a custom build. You are not choosing between speed and control – you get both.
How SDK.finance Helps Start a Digital Bank Faster
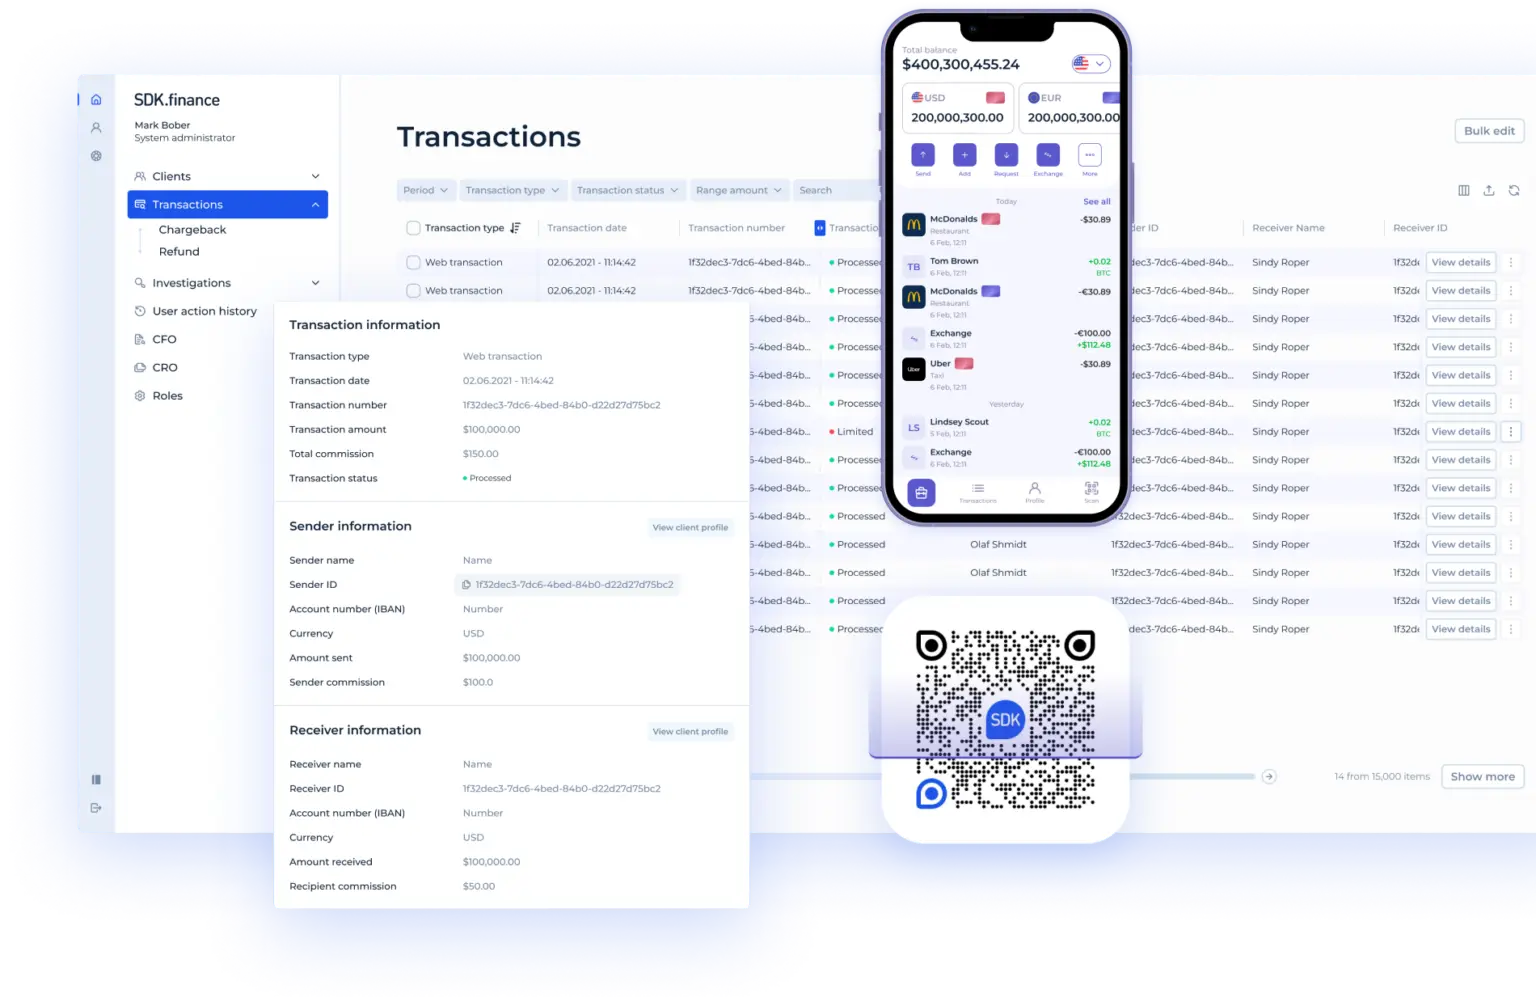
Most fintech teams spend the first 12-18 months doing work that has already been done before: designing ledger logic, building fee engines, writing back-office tooling, wiring role-based access, and connecting currencies and providers. This is not differentiated work. It is table stakes – and it consumes budget that could go toward customer experience, compliance quality, distribution, and partnerships. SDK.finance exists to solve that problem.
What is SDK.finance?
SDK.finance is a ready-to-use fintech software platform built on 15+ years of financial infrastructure engineering, helping companies launch digital banks, neobanks, wallets, payment products, and embedded finance solutions faster with core infrastructure, APIs, back office, mobile/web interfaces, and SaaS or source-code delivery for full vendor independence.
The core proposition is simple: you bring the license strategy, brand, regulated partners, and business model. SDK.finance provides the financial infrastructure that makes it work.
What you get on day one
- Multi-currency accounts and wallets.
- Transaction processing with ledger-grade integrity.
- Configurable fee and limit system.
- Back-office portal for operational control.
- Merchant portal for merchant-facing workflows.
- Mobile app and mobile web app for end users.
- 650+ APIs for product and provider integrations.
- KYC/KYB workflows and compliance statuses.
- Provider and contract model for payment and banking integrations.
- Reporting, reconciliation, notification templates, roles, and permissions.
- PCI DSS certified infrastructure for secure payment data handling.
- ISO 27001:2022 certified information security management.
- GDPR-ready architecture and processes for personal data protection.
Source-code license for 100% vendor independence
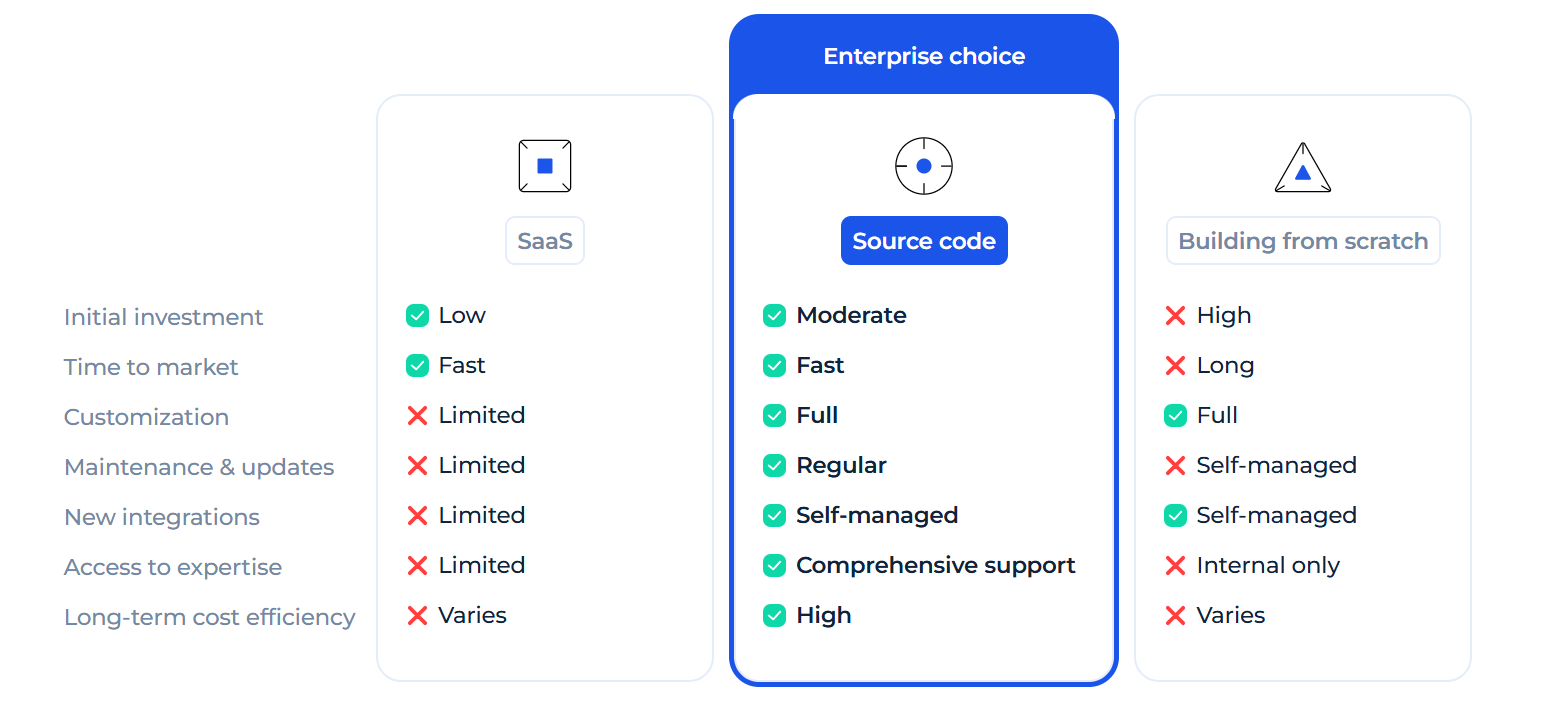
For executive teams evaluating long-term technology strategy, the source-code option addresses one of the biggest risks of working with any third-party fintech platform: lock-in. With SDK.finance source-code delivery, your organization can own the codebase, deploy in its own infrastructure, integrate directly with providers, build custom modules, and evolve the platform on its own roadmap.
This is the difference between renting infrastructure and owning it. SaaS is excellent for speed. Source code is stronger when the business needs technology independence, custom compliance logic, specific deployment requirements, or long-term product control.
The business case for using a platform
The ROI argument is straightforward. A custom build of the infrastructure SDK.finance provides – ledger, fees, limits, roles, currencies, back office, APIs, and mobile interfaces – can take years and cost millions to reach production quality. SDK.finance compresses that to a fraction of the time and cost, while keeping the product flexible enough for serious fintech ownership.
That budget delta becomes available for the work that actually differentiates your product: distribution, compliance, customer experience, market entry, and partnerships.
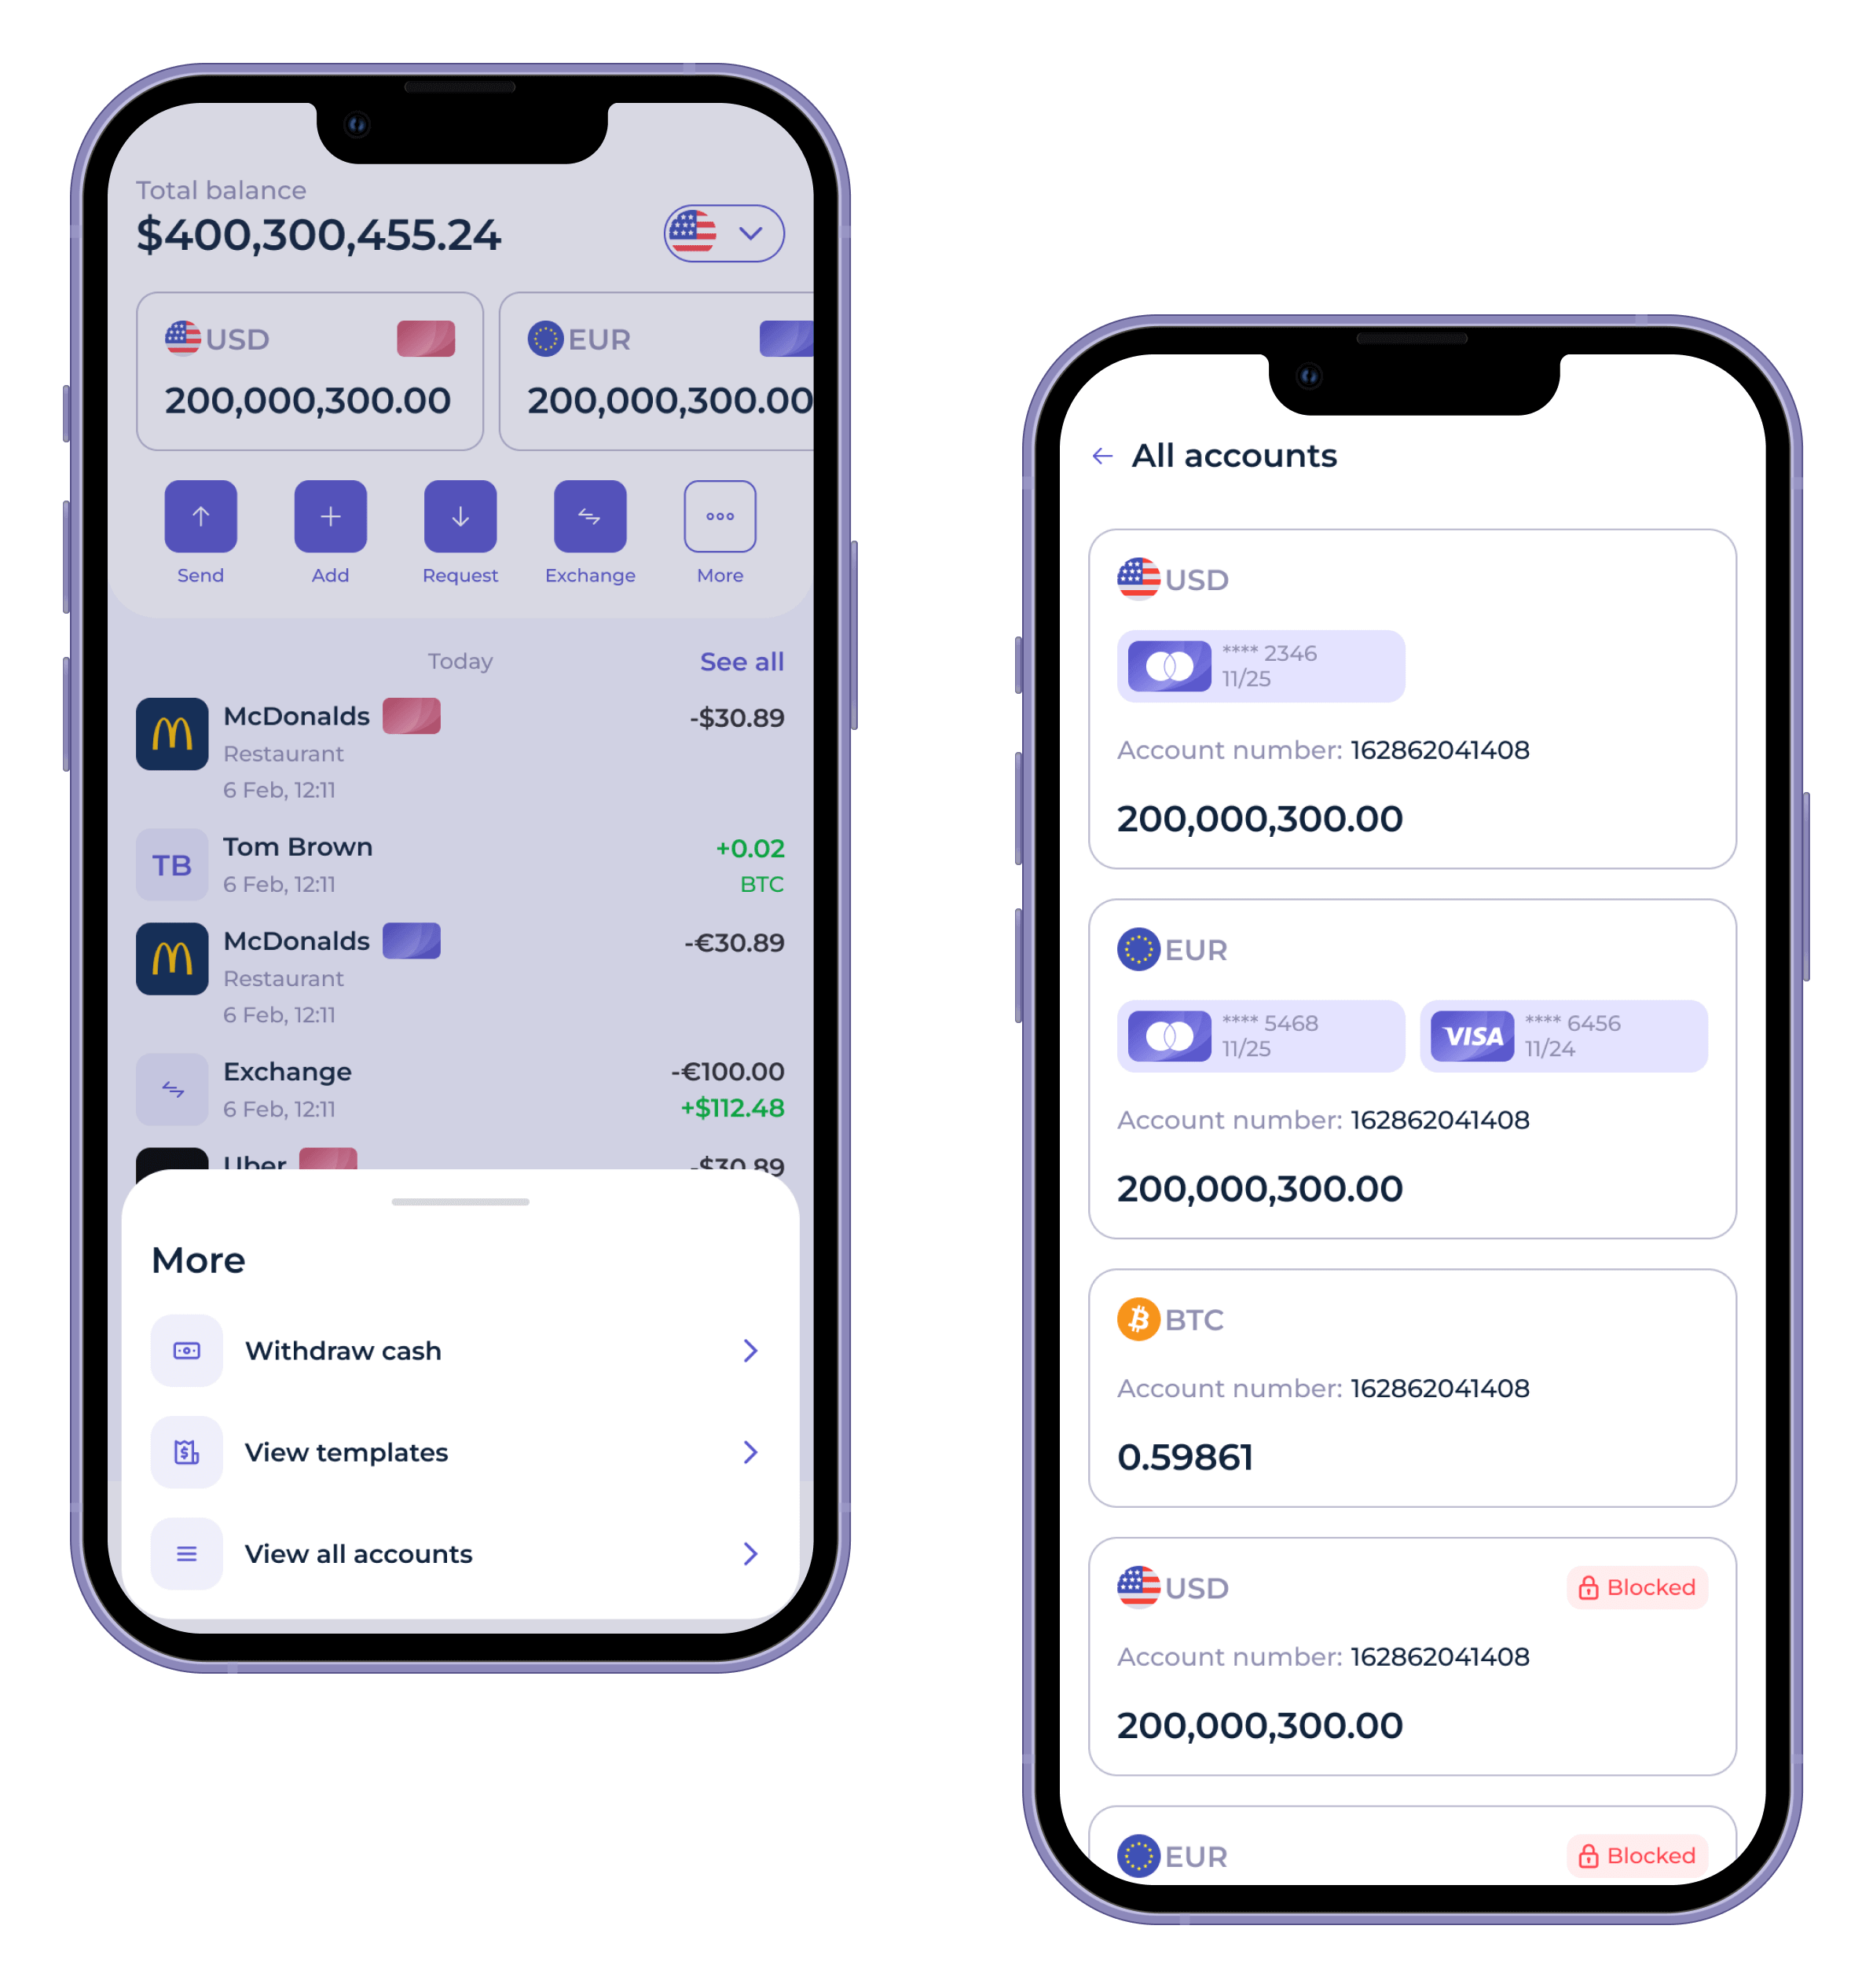
To see the customer-facing product layer, watch the SDK.finance mobile banking app demo:
Proven FinTech and Banking Software Expertise
-
Recognized by leading FinTech and banking technology awards. SDK.finance has been recognized by major industry programs, including PayTech Awards 2026, Banking Tech Awards 2025, and other international FinTech and banking software awards.
-
Regularly featured among top banking software providers. SDK.finance has been included in industry rankings and market reports such as the Everest Group Top 50 Core Banking Technology Providers 2026 and other core banking systems report.
-
Proven in launched products and high-volume processing. SDK.finance software powers implemented financial products across the US, Canada, the EU, the UK, and MENA; one Saudi Arabian payment system built on SDK.finance processes around 75% of national payments, demonstrating scalability for high-volume, mission-critical transaction processing.
SDK.finance provides core banking infrastructure with ledger, payments, wallets, ready applications and flexible deployment options
Talk to Our TeamCommon Mistakes When Starting a Digital Bank
- Choosing the license path too late. Regulatory applications take months to years. Build clarity on license strategy before product architecture is locked.
- Building the mobile banking app without the ledger and back office. A customer-facing app without a ledger, fee engine, reconciliation, and operational tooling is a prototype, not a bank.
- Underestimating provider orchestration. Card processors, payment rails, KYC vendors, AML tools, and banking partners all require contracts, integrations, monitoring, and contingency plans.
- Treating compliance as manual work. AML monitoring, KYC workflows, and reporting need to be automated, auditable, and operationally visible.
- Ignoring vendor lock-in. Source-code ownership, data portability, and exit rights are strategic issues, not procurement details.
- Overbuilding before product-market fit. Fewer products, fewer markets, and fewer integrations at launch are usually faster and cheaper.
Based on SDK.finance’s 15+ years of experience supporting the launch of digital banking and fintech products, the biggest failure pattern is treating speed as the strategy: teams go live quickly, but struggle to scale because ledger logic, reconciliation, compliance workflows, provider orchestration, and operational visibility were not designed for growth from day one.
The stronger approach is to start with infrastructure that is ready not only for launch, but for the next stages of volume, complexity, and market expansion. If you are planning a digital bank, neobank, wallet, or payment product, SDK.finance can help you choose the right platform model and move from idea to launch with a scalable foundation.
Book a demo to see how SDK.finance can support your digital banking launch.